Insights & Trends

Win the Golden Quarter: 8 Consumer Spending Predictions
Turn four years of UK purchase trends into your Q4 advantage.
The Golden Quarter is stretching out.
The Golden Quarter is no longer defined by a single shopping peak. Cardlytics analysed four years of UK purchase data, and consumer shopping trends point to a longer, steadier shopping season. Easing utility bills have unlocked more flexibility for households, meaning strong consumer resilience is hiding behind a seemingly flat top-line.
−0.8%
Overall tracked spending contracted slightly to £31.8bn — a decrease driven by falling utility costs rather than a lack of consumer confidence.
+1.7%
Excluding utilities, core quarterly spending grew. Discretionary purchasing remained resilient.
65p
For every £1 households saved on essential bills like energy and broadband, 65p was redirected into other sectors.
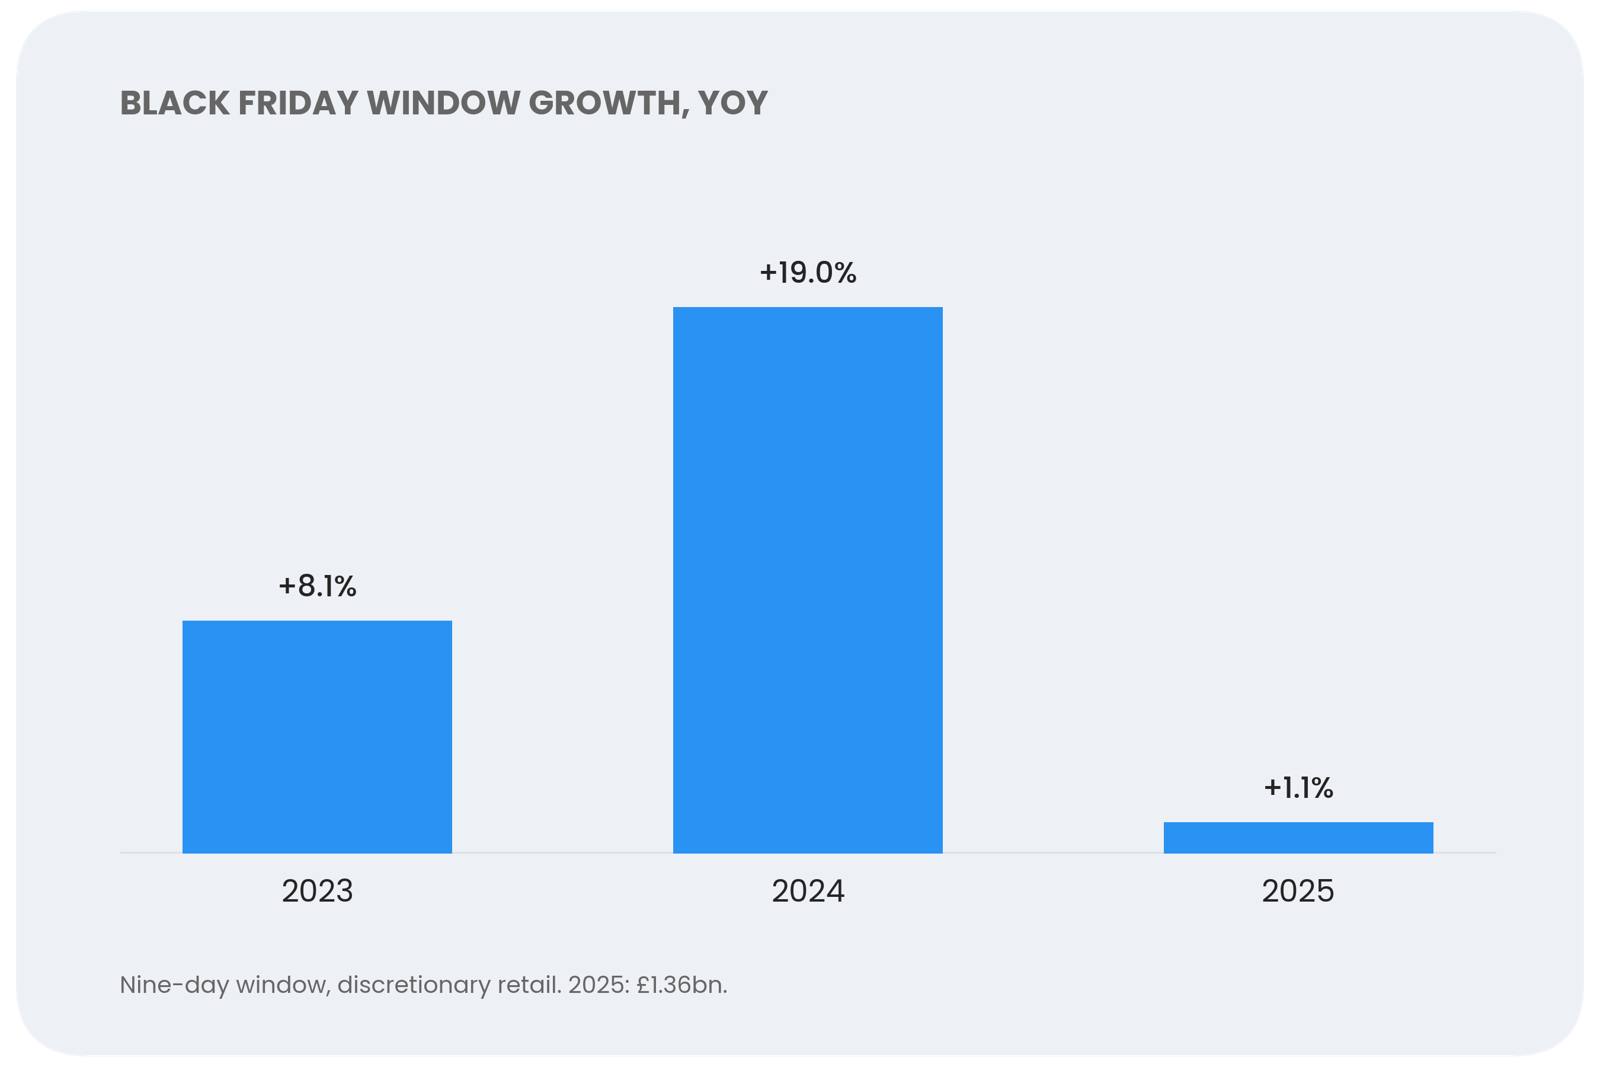
+1.1%
The traditional nine-day Black Friday window saw modest growth, levelling out after the 19% surge the prior year.
Three of our eight predictions
1. Black Friday won't grow: It is now a flat event. Shoppers are spending more in the weeks before it starts.
2. Discounters win Christmas dinner: Discount supermarkets will pass 10% of all grocery spend, hurting the mid-market brands.
3. The party moves to the pub: Sit-down dining is dropping. Pubs will hold steady, while fast food only grows because prices went up.
Get all eight predictions and how to win
The full report covers every prediction, including why retail will take more share, a record quarter for gaming and why next summer gets booked before Christmas, with the data behind each one, its trend rating and what it means for advertisers. Plus the one to watch: will December stall again?
Cardlytics Banking Loyalty Index 2026
From loyalty to relevance: Why personalised rewards matter more than ever for UK banks
From loyalty to relevance: Why personalised rewards matter more than ever for UK banks
UK consumers may feel loyal to their bank, but that loyalty is increasingly conditional.
New research from Cardlytics, based on a nationally representative survey of 4,000 UK adults, shows that while most customers are not actively planning to switch, many are open to reassessing where they bank when the value is clear.
Two thirds of consumers (65%) say they feel loyal to their main bank, and 60% say they are unlikely to switch in the next 12 months. But that stability should not be mistaken for permanence. More than half (57%) have switched their main bank account at some point as an adult, and many now spread their money across more than one provider.
The result is a banking market where retention is no longer just about keeping customers from leaving altogether. It is about staying relevant in more of their everyday financial decisions.
Trust and service still matter, but they are now the baseline
When asked what keeps them with their current bank, UK consumers are most likely to cite good customer service (40%), brand trust and reputation (35%), and the quality of mobile or online banking (32%).
These are the foundations of a strong banking relationship. They help explain why customers stay put, particularly older generations. For example, Baby Boomers are significantly more likely to say customer service is a key reason they stay with their bank (50%).
But these factors are increasingly expected. They are essential to retention, but on their own they may be less effective at creating real competitive advantage.
Unlock the full Cardlytics Banking Index 2026
The shift from passive loyalty to active relevance is changing how the UK banks. To read the full analysis on how financial value triggers action, the impact of personalised rewards on 18 to 34 year olds, and why loyalty is no longer exclusive, download the complete report below.
Get the full insights to discover:
- The Switching Triggers: The specific financial incentives driving 25% of Gen Z to reconsider their bank.
- The Personalisation Opportunity: How tailored rewards can increase retention by up to 55% for key demographics.
- The Visibility Challenge: Why 22% of customers are unaware of the rewards their banks already offer.
- Multi-banking Trends: Why customers are spreading their finances and how to capture a greater share of wallet.
Where have all the shoppers gone?
After two years of post-pandemic recalibration, UK consumers are still spending. But they are becoming more selective in where, when and why they do so.
Where have all the shoppers gone?
How UK shoppers are narrowing their choices — and what it means for growth
After two years of post-pandemic recalibration, UK consumers are still spending. But they are becoming more selective in where, when and why they do so.
Cardlytics’ latest State of Spend report draws on first-party purchase data from 23 million UK bank customers across the spring and summer period.
What it shows is simple: retail growth remains present, but increasingly uneven. Categories that feel essential, convenient or low-risk continue to attract spend. More discretionary and deferrable purchases are coming under greater pressure.
This is less a story of demand disappearing and more one of decision-making narrowing. For retailers and brands, growth will depend less on broad consumer momentum and more on securing a place in a smaller set of deliberate purchasing moments.
Essentials: fewer trips, tighter control
Essential categories remain the most resilient part of the market. But the pattern of spending suggests households are becoming more deliberate in how they manage everyday needs. Growth is still there — it is just concentrated in channels that offer either convenience at scale or a clearer sense of value.
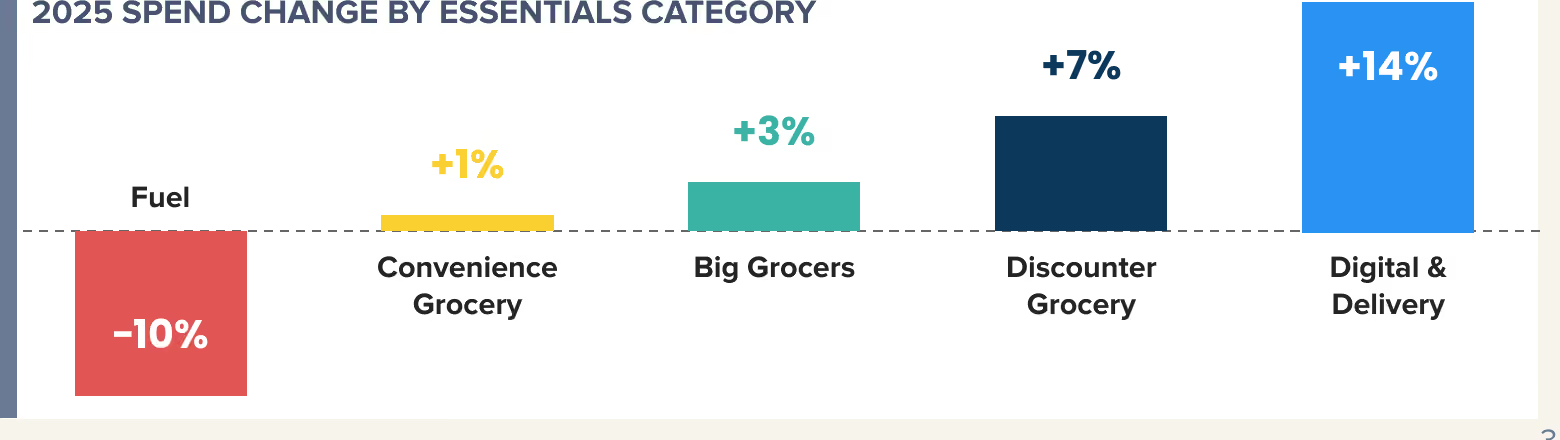
The strongest performance continues to come from Digital & Delivery Grocery, where spend rose 17% in 2024 and 14% in 2025. Transactions also grew strongly, pointing to a channel still benefiting from continued adoption and slightly larger baskets.
Discounter Grocery shows a similar pattern, with spend up 9% in 2024 and 7% in 2025, supported by steady transaction growth. The category continues to act as a dependable value channel for households managing budgets carefully.
Among Big Grocers, growth is more subdued — 6% in 2024, slowing to 3% in 2025 — while transactions moved broadly flat. Spending is being held up by larger baskets rather than more visits. Convenience Grocery has come under greater pressure still, with trips down around 3%.
Fuel is the clearest sign of retrenchment within essentials. Spend declined 5% in 2024 and 10% in 2025, with early 2026 data indicating this behaviour is continuing.
Cardlytics analysis
Essential spend is still being protected, but the shape of that spend is changing. Consumers are concentrating everyday purchasing into channels that help them feel organised or in control — whether that’s delivery-led convenience or discounter-led value.
For marketers, the opportunity is less about generating additional need and more about intercepting planned purchase moments with a clear reason to choose one retailer or brand over another. In a market where fewer shopping occasions carry more weight, securing a greater share of each visit matters more.
Retail: a resilient base, but narrowing engagement
Retail continues to grow — but that growth is becoming more uneven. The strongest performance is increasingly concentrated in categories that feel accessible, repeatable or easy to justify. Traditional and aspirational areas are finding it harder to sustain engagement.
Make-up & Beauty remains one of the clearest areas of resilience. Spend rose 11% in 2024 and 8% in 2025, with transactions also moving in the right direction. It’s one of the few categories where shoppers still see room for smaller, more manageable discretionary purchases.
Online Fast Fashion continues to expand, up 14% and 9% across the two years, though baskets have softened slightly — shoppers engaging more frequently but with tighter control on basket size. Marketplaces are another strong area of growth, reinforcing their role as a flexible, value-conscious route to purchase.
Elsewhere, the picture tightens. High Street Fashion growth has slowed and transactions have flattened. Department Stores saw spend fall 3% in 2024 and 4% in 2025, pointing to an ongoing footfall challenge. And Luxury / Designer Fashion spend declined 6% in 2024 and 8% in 2025 — purchases are still happening, but among fewer shoppers, less often.
Cardlytics analysis
The categories still growing are not necessarily those with the strongest brand pull. They are the ones most aligned with how consumers want to shop now: flexibly, frequently and with lower perceived risk.
For brands, that raises the importance of relevance, value communication and mission-based targeting over broader assumptions about seasonal demand. In a more selective market, success will depend less on broad visibility alone and more on giving shoppers a clear, immediate reason to engage.
Household: from upgrade to upkeep
Across home-related categories, the shift from 2024 into 2025 points to a more cautious consumer mindset. Spending hasn’t disappeared — but households are more willing to maintain and replace than to embark on larger, more discretionary home purchases.
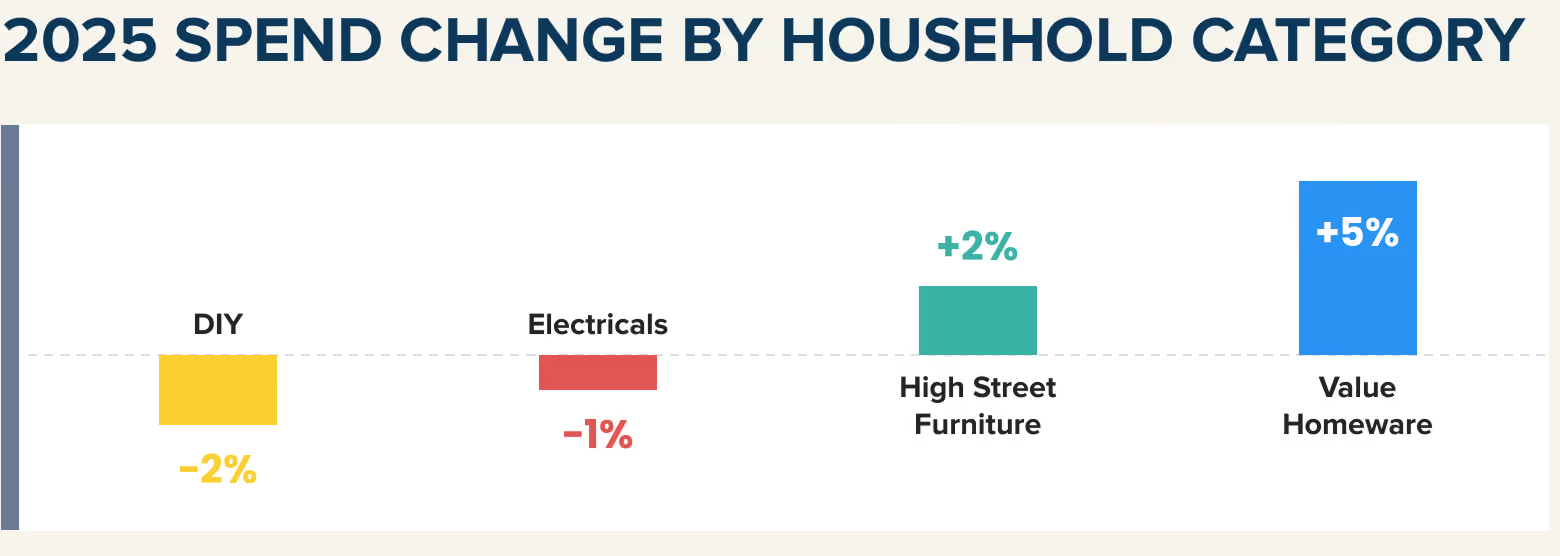
Value Homeware has remained relatively stable, up 9% in 2024 and 5% in 2025. High Street Furniture shows a clearer slowdown, moving from 6% growth to 2%, with spend concentrating in fewer, higher-value occasions.
The pattern is more pressured in DIY. After 3% growth in 2024, spend moved into a 2% decline in 2025, with transactions down around 5%. Electricals follow a similar trajectory — from 4% growth to a 1% decline — with purchases increasingly concentrated in fewer, more considered buying moments.
Cardlytics analysis
In home-related categories, demand increasingly looks tied to maintenance, replacement and justified necessity rather than inspiration or upgrade. That changes what effective messaging looks like.
Brands here may need to focus less on aspiration and more on practicality, durability and timely relevance if they want to convert consumers who are clearly weighing whether a purchase can wait. The strongest opportunities come from moments where need is immediate and the value exchange is clear.
Wider discretionary: where the drop-off is most visible
The clearest signs of pressure appear outside the core retail categories — in areas where spending is most optional and easiest to postpone. Here the challenge is not how much consumers spend when they engage, but whether they enter the category at all.
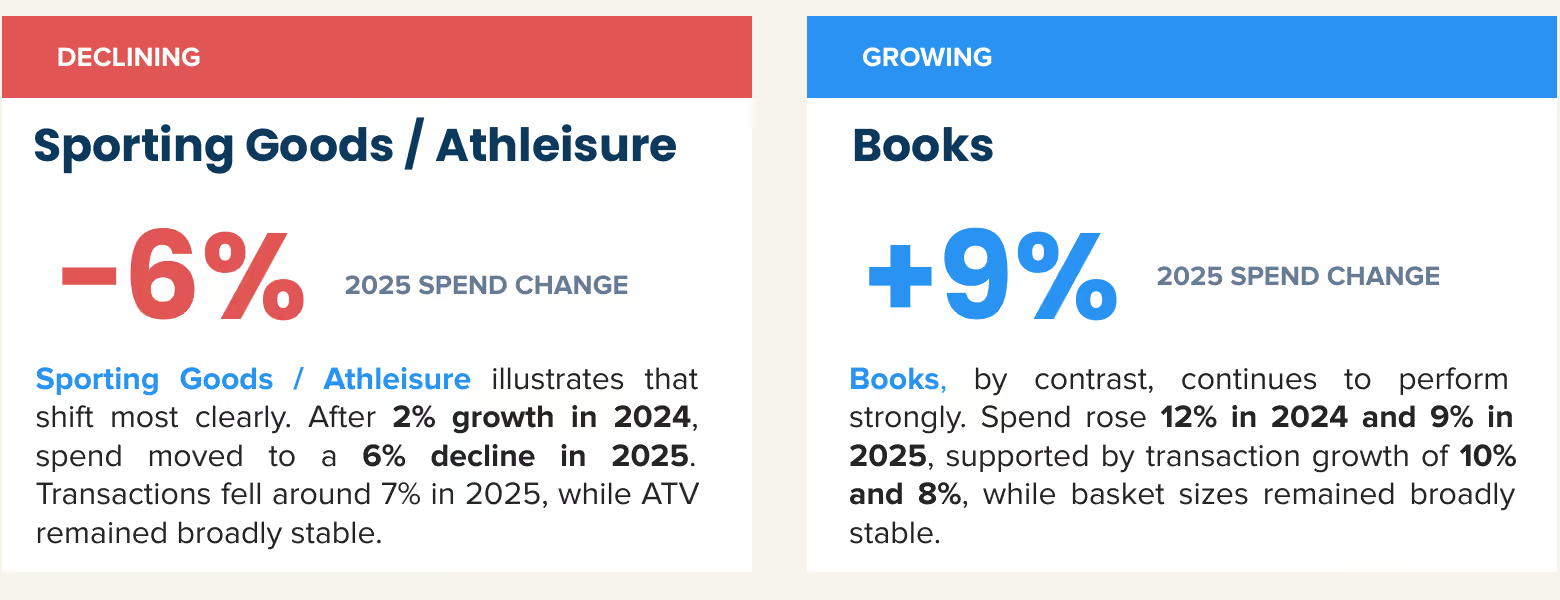
Sporting Goods / Athleisure illustrates the shift most clearly. After 2% growth in 2024, spend moved to a 6% decline in 2025, with transactions down around 7% while ATV stayed broadly stable. The pressure is being driven by fewer shoppers choosing to participate — not by smaller baskets.
Books, by contrast, continues to perform strongly, up 12% in 2024 and 9% in 2025. It remains one of the clearest examples of a discretionary category where engagement holds up — consumers are still willing to spend where purchases feel lower-cost, familiar or easy to justify.
The issue is no longer simply whether shoppers can spend, but which categories still make the cut.
Cardlytics analysis
For discretionary categories, the core challenge is re-engagement. When consumers are reducing the number of optional purchases they make, brands need stronger triggers to prompt participation in the first place.
That may mean leaning harder into immediacy, occasion-based relevance, perceived value or more functional reasons to buy — rather than assuming promotions alone will unlock demand. Growth depends less on broad category momentum and more on giving consumers a compelling reason to opt in at all.
Looking ahead into 2026
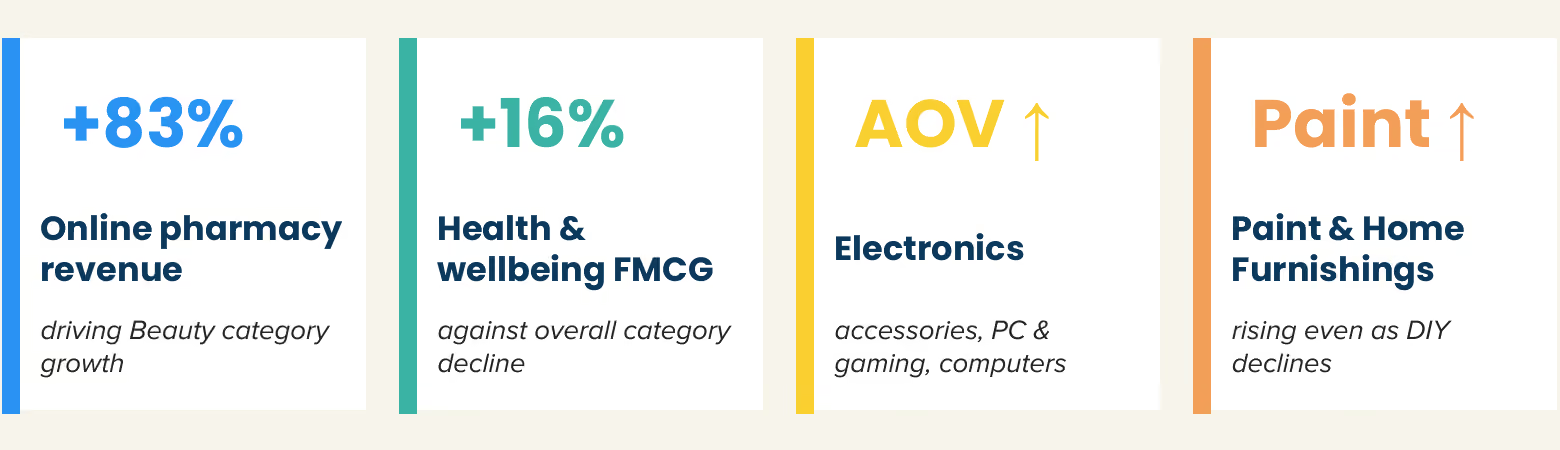
Early 2026 performance is already pointing to where the narrowing of shopper demand is concentrating. Online pharmacy revenue is driving Beauty category growth. Health & wellbeing FMCG is up against overall category decline. Electronics AOV is rising on accessories, PC and gaming. And Paint & Home Furnishings are rising even as DIY declines — a clear signal that the channel and use-case shifts identified in this report are continuing.
Fewer decisions, higher stakes
The summer shopper has not disappeared, but the number of decisions they appear willing to make has narrowed.
Across the market, the strongest performance is coming from categories that feel essential, convenient or easy to justify, while more deferrable and aspirational purchases are facing greater pressure. That does not point to a collapse in consumer demand — it points to a consumer mindset that is becoming more selective about where spending feels worthwhile.
For retailers and brands, that creates a more competitive environment. Growth is no longer just about being present at the point of purchase — it is about being relevant enough to be included in a smaller set of deliberate decisions. In that context, value, timing and clarity matter more, particularly in categories where engagement can no longer be taken for granted.
How marketers should show up
01. Protect existing shoppers first
Shoppers don’t leave in one move — they drift. Transaction data already shows who’s slipping. Reaching a lapsed shopper around their next likely need window is cheaper than finding a replacement, and more effective than broad re-acquisition.
02. Growth sits in small, repeat purchases
The categories still expanding are the ones where the purchase feels small, familiar and easy to justify. Find the version of your product that fits a smaller, more frequent moment — something a shopper says yes to without deliberation.
03. Solve for participation, not basket size
The harder question isn’t what a shopper spends when they show up — it’s whether they show up at all. Discounting rarely pulls someone into a category they’ve stepped out of. An immediate, tangible need does.
The brands best placed to outperform will be those that understand which purchase moments consumers still prioritise — and can show up in those moments with a clear and compelling reason to buy.
Talk to Cardlytics about how purchase intelligence and card-linked offers can help your brand secure a place in a smaller, more deliberate set of consumer decisions — www.cardlytics.com
The Golden Quarter is Changing: Inside the 2025 State of Spend
The UK’s peak retail season is evolving. Consumers are still spending, but they’re more selective, strategic, and values-driven than ever before. Based on spend data from over 23 million UK bank accounts and nationally representative research, Cardlytics' State of Spend report uncovers what’s shaping the 2025 Golden Quarter — and where brands should focus to win.
Headline Trend Summaries (With Light Stats)
1. Black Friday is no longer the main event
The era of single-day shopping spikes is fading. Our data reveals that consumers are spreading spend across weekends and early December instead. Brands focused only on the Friday are missing the bigger picture.
2. Gifts that matter and don’t just impress
Over half of consumers say they’re choosing meaningful or practical gifts this year. Beauty and books are holding strong, while luxury and electrical categories are losing ground.
3. Fashion is fragmenting
Fast fashion still performs, but growth is slowing. Shoppers are shifting toward resale platforms and marketplaces that offer affordability and sustainability in one.
4. Grocery is about confidence, not just cost
Spend is still rising across grocery - but discounters, delivery services, and high-end grocers are outpacing traditional supermarkets. Value is no longer just about price; it’s about trust and convenience.
Consumers are still buying. They’re just doing it on their terms. The winners in 2025 will meet them where they are — with relevance, value, and visibility.”
Want the full data?
The full report includes:
- Category-by-category breakdowns from 2022 to 2024
- 2025 retail forecasts across 14 key sectors
- Consumer behaviour insights and shopping intent
- Strategic recommendations for campaign planning
Download the Full Report
Loyalty Movement Report: Apparel
Customer behavior isn’t fixed—customers shift between loyalty segments over time. Understanding these shifts helps identify churn and informs strategies to nurture relationships and move customers to higher loyalty segments. In our Loyalty Movement Report, we dive into customer behavior in the Apparel category to better understand engagement over time by analyzing more than $17B in consumer spend behavior.*
Apparel: Stop Taking Customer Loyalty for Granted
Introduction
In our previous report, Redefining Customer Loyalty, Cardlytics defined loyalty as a consumer’s preference for a merchant over its competitors. We analyzed $160B in spending across six industries to measure customer loyalty and spending patterns with both loyal and non-loyal customers.
But customer behavior isn’t fixed—customers shift between loyalty segments over time. Understanding these shifts helps identify churn and informs strategies to nurture relationships and move customers to higher loyalty segments. In our Loyalty Movement Report, we dive into customer behavior in the Apparel category to better understand engagement over time by analyzing more than $17B in consumer spend behavior.*
Apparel Category Loyal Customers
On average, 61% of a merchant’s customers are not actually loyal. But the loyal segment has a much higher share of wallet (85%) than a not loyal segment (21%).
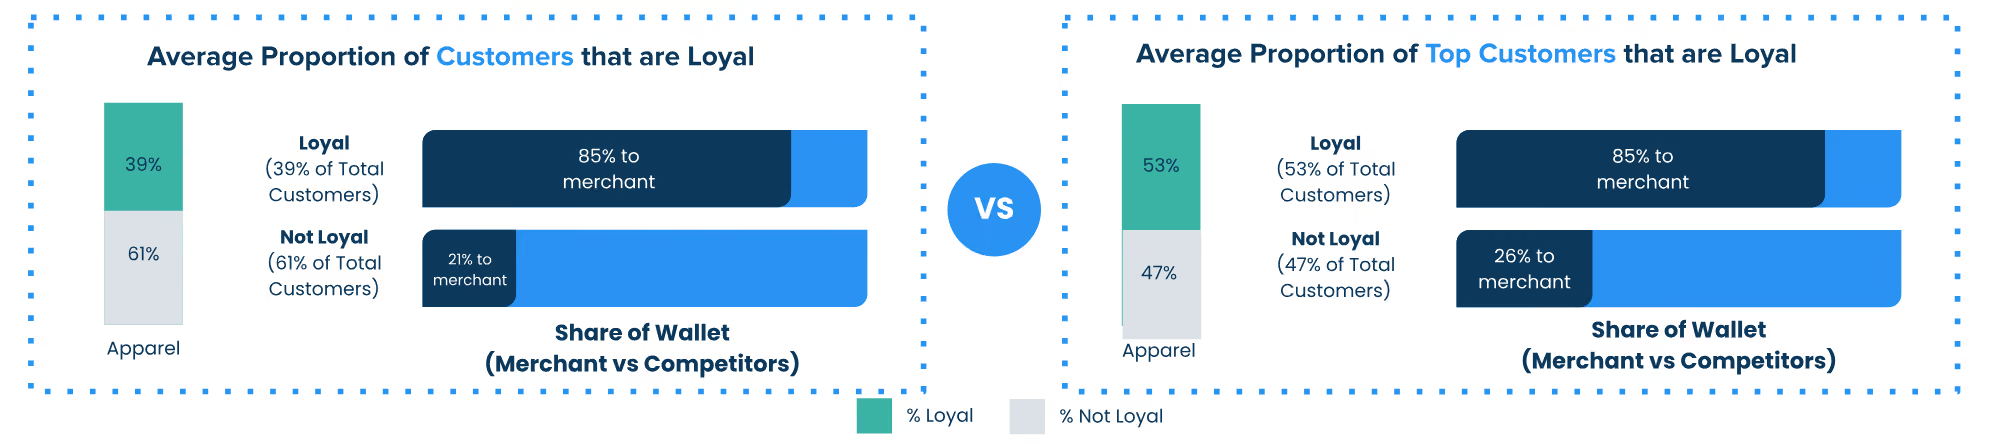
Top Customers (top 10% of most frequent transactors) show a +6 point uptick as loyal vs not loyal customers. But the loyal customer segment shows more than 3x higher share of wallet.
Findings
We looked into purchase data at all Apparel brands in the US over the last 8 quarters (Q1-23 through Q4-24) on a quarter by quarter basis to see whether even the “most loyal” customers showed changes in their purchase behavior.
Apparel Loyalty Movement
Overall, quarter over quarter, 41% of customers tend to remain in their existing segments while 16% increase or decrease their loyalty to a merchant. Yet there is much more extensive customer loyalty movement within the “not loyal” segments.
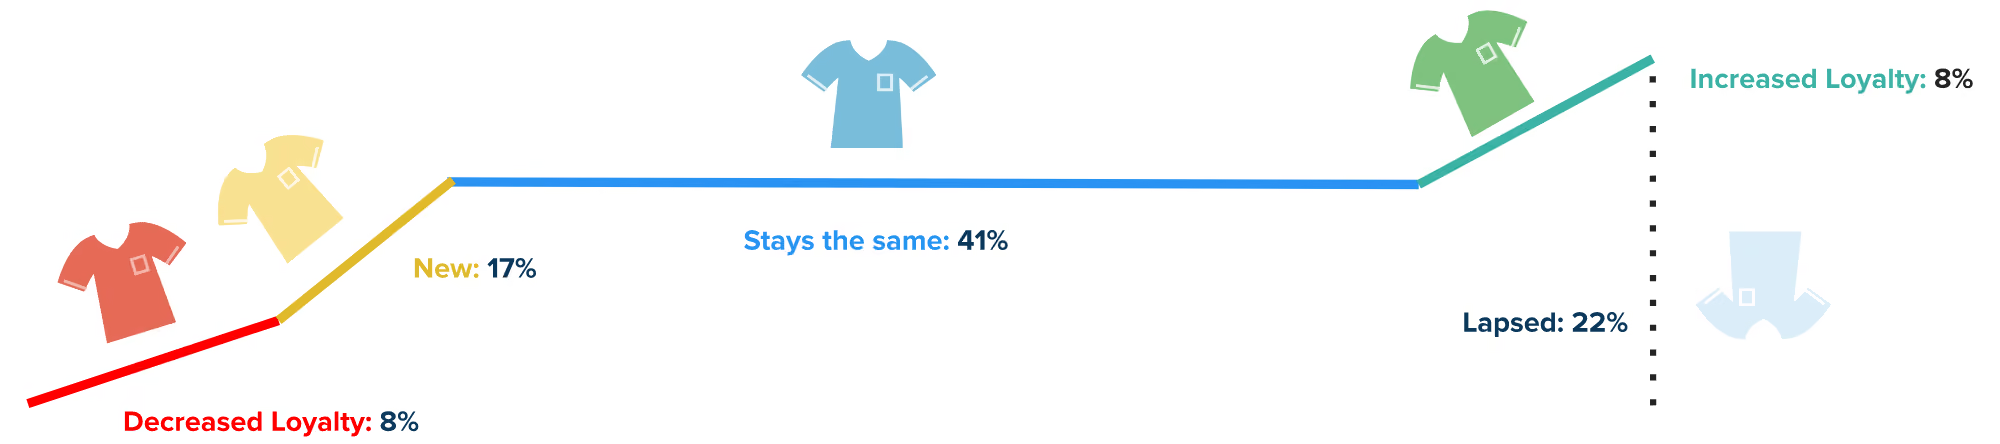
Segment Movement
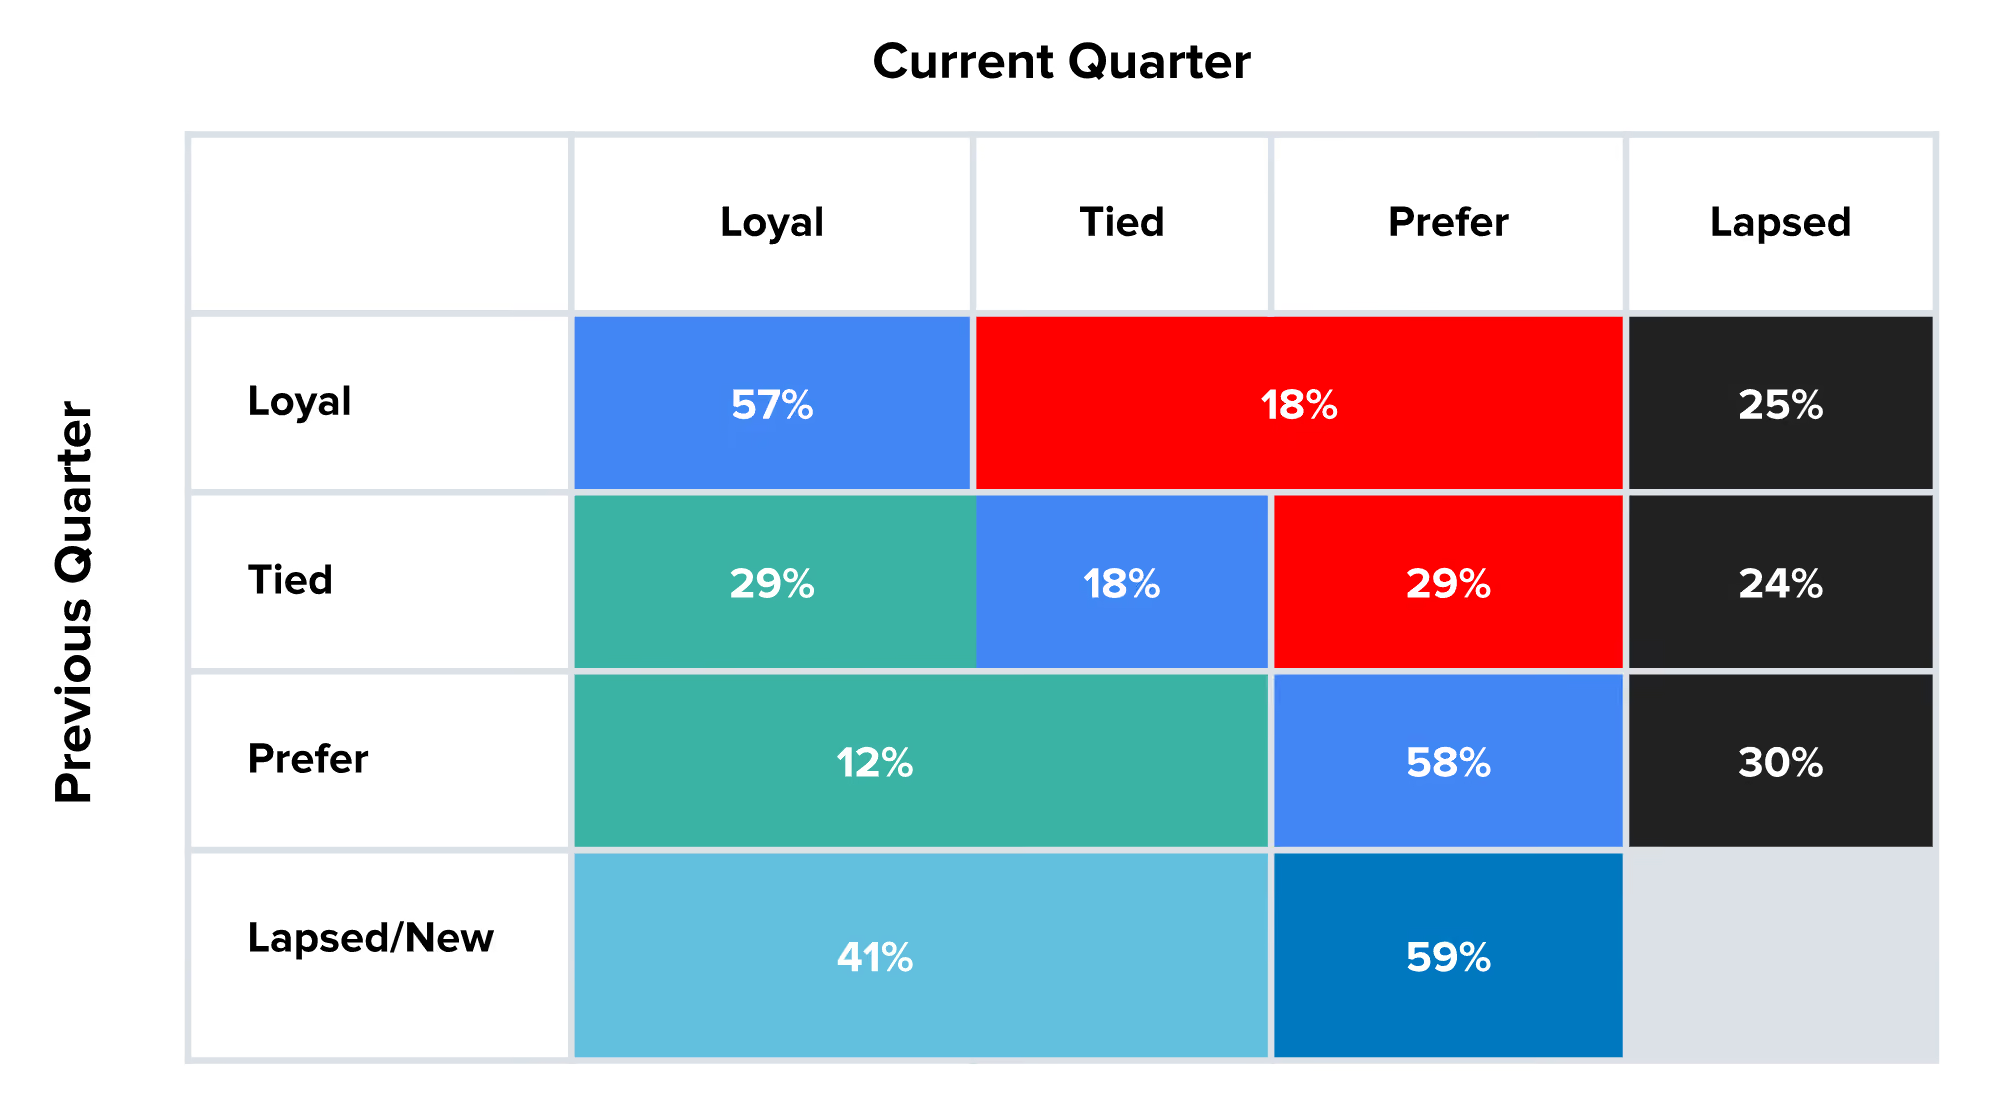
While all segments show purchase behavior movement, the Tied segment (part of Not Loyal customers) shows the most movement - both up (29%) and down (29%) - into other segments.
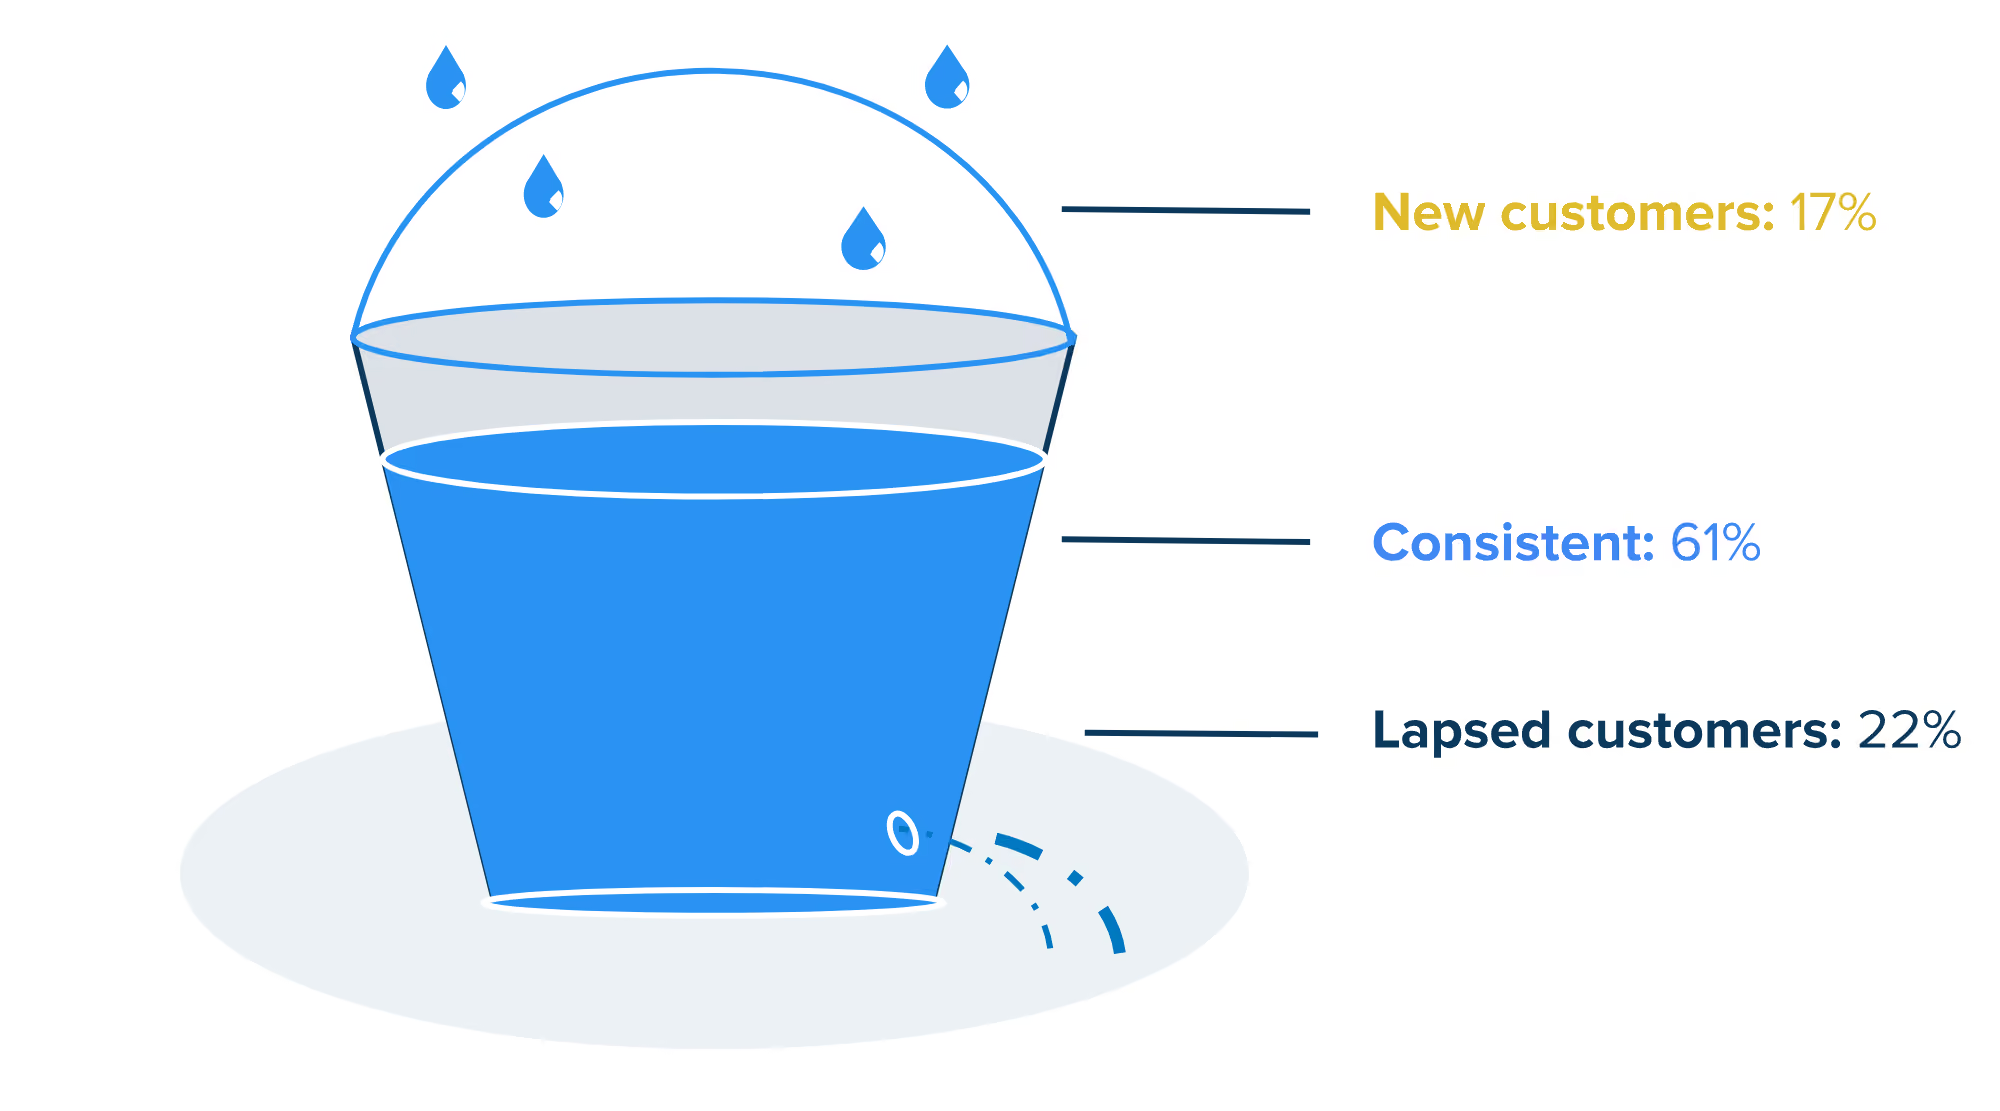
Apparel Leaky Bucket
Apparel brands are acquiring new customers yet even more existing customers are moving into the lapsed tier. This cycle can be reversed by continuing to nurture existing customers.
Diving deeper into the individual segments tells us:
- Loyal customers and those that Prefer the competition are the most rigid (with 57% and 58% staying the same, respectively). Those customers that are Tied have the greatest propensity for a behavior change (with only 18% staying the same).
- While the most Loyal customers show a 25% lapsed rate at similar levels as Tied, this is most likely not connected to churn vs connected to cadence of shopping behavior (maybe they don’t buy clothes every that frequently).
Definitions of Customer Segments
Loyal Customers
Loyal: Only shop with a specific brand, or have the highest share of wallet with a given brand and relative rank is lower than all other brands in consideration set
Not Loyal Customers
Tied: Similar relative ranks to 2 or more brands regardless of share of wallet ranking
Prefer: Lower share of wallet and higher rank than other brands in their consideration set
Lapsed: Shopped historically but do not shop currently, as defined by the analysis time period
New: Shop currently but have not shopped historically, as defined by the analysis time period
Takeaways
Marketers know it’s more costly to acquire or re-acquire customers than to keep existing ones engaged. When brands neglect current customers, they risk losing them and undoing past investment yet the reasons why a customer might “lapse” is different depending upon their loyalty tier. Loyalty is fragile and demands ongoing effort as competition is always close by. To stay top of mind, marketers must continuously nurture relationships, understand customer needs, and offer seamless experiences. To foster loyalty with your customers, consider these recommendations:
- Use an “always on” strategy to keep customers engaged, regardless of purchase frequency.
- Regularly update/refine customer segments and adjust reward offers to keep them engaged.
- Use targeted campaigns to boost loyalty and revenue.
Cardlytics can deliver a comprehensive Customer Loyalty Analysis with insights into customer behavior and movement across defined loyalty segments. Contact us for more details.
* For this report, we've selected the entire Apparel category in our data, collectively representing $17bn in annual card spend. This sample differs from the previous Customer Loyalty Analysis report.
About Cardlytics
Cardlytics (NASDAQ: CDLX) is a commerce media platform, powered by our publishers’ first-party purchase data, that makes commerce smarter and more rewarding for everyone. We offer a range of solutions to help advertisers and publishers, including financial institutions, grow and strengthen customer loyalty. With visibility into approximately half of all card-based transactions in the U.S. and a quarter in the U.K., Cardlytics enables advertisers to engage consumers at scale and drive incremental sales through our industry-leading financial media network. Publisher partners can enhance their platforms with relevant and personalized offers that improve the shopping experience for their customers. Cardlytics also offers identity resolution capabilities through Bridg, which helps convert anonymous shoppers into known and reachable customers. Headquartered in Atlanta, Cardlytics has offices in Menlo Park, Los Angeles, Champaign, New York and London. Learn more at www.cardlytics.com or follow us on LinkedIn.
Loyalty Movement Report: Airlines
Customer behavior isn’t fixed—customers shift between loyalty segments over time. Understanding these shifts helps identify churn and informs strategies to nurture relationships and move customers to higher loyalty segments. In our Loyalty Movement Report, we dive into the Airline category to better understand engagement over time by the entire more than $58B in consumer spend behavior.
Airlines: Unpacking the State of Customer Loyalty
Introduction
In our previous report, Redefining Customer Loyalty, Cardlytics defined loyalty as a consumer’s preference for a merchant over its competitors. We analyzed $160B in spending across six industries to measure customer loyalty and spending patterns with both loyal and non-loyal customers.
But customer behavior isn’t fixed—customers shift between loyalty segments over time. Understanding these shifts helps identify churn and informs strategies to nurture relationships and move customers to higher loyalty segments. In our Loyalty Movement Report, we dive into the Airline category to better understand engagement over time by the entire more than $58B in consumer spend behavior.*
Airline Category Loyal Customers
On average, 39% of a merchant’s customers are not loyal. Yet the loyal segment shows extreme loyalty when it comes to share of wallet (95%) where as a not loyal segment does not (28%).
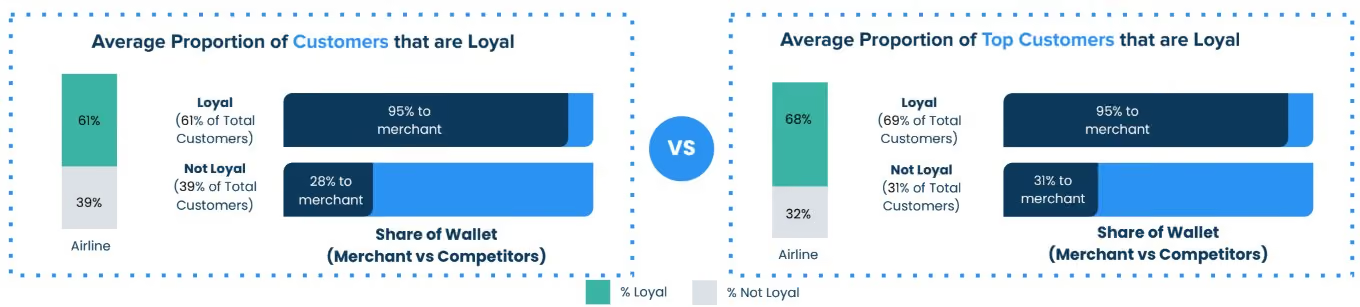
Top Customers (top 10% of most frequent transactors) are heavily loyal - 2/3. And that loyal customer segment shows the same extreme loyalty in terms of share of wallet as all customers.
Findings
We looked into purchase data at all Airlines in the US over the last 8 quarters (Q1-23 through Q4-24) on a quarter by quarter basis to see whether even the “most loyal” customers showed changes in their purchase behavior.
Airline Loyalty Movement
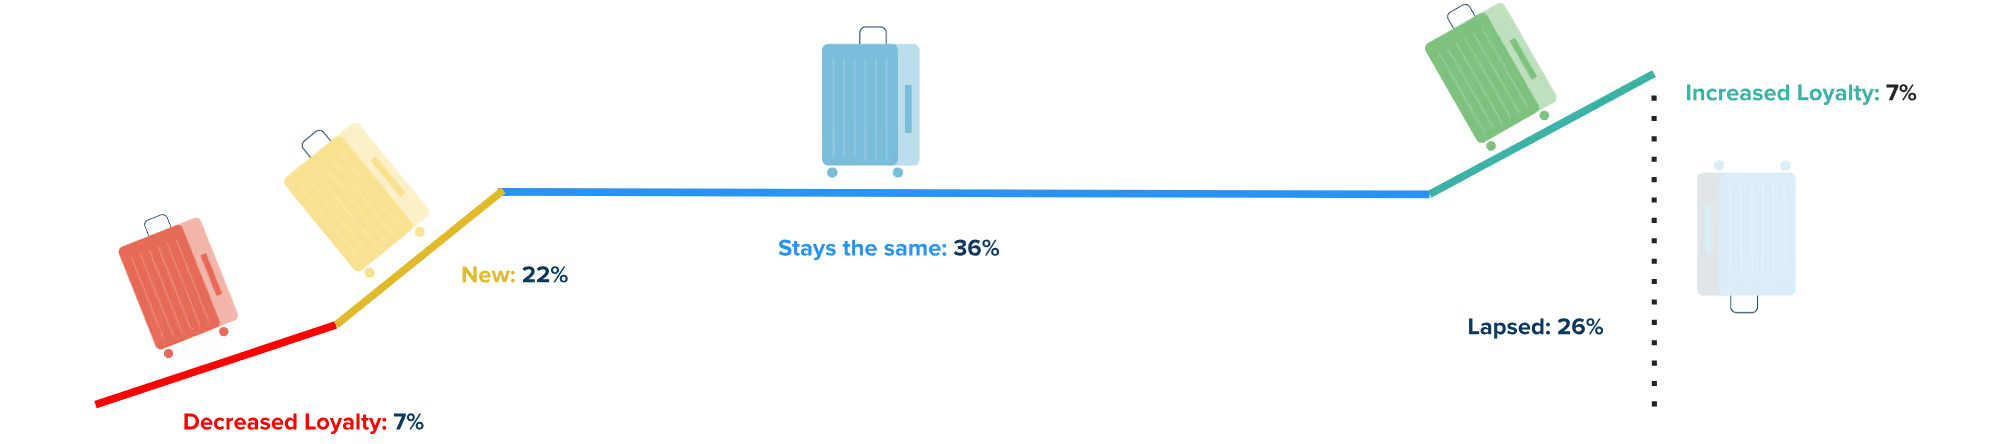
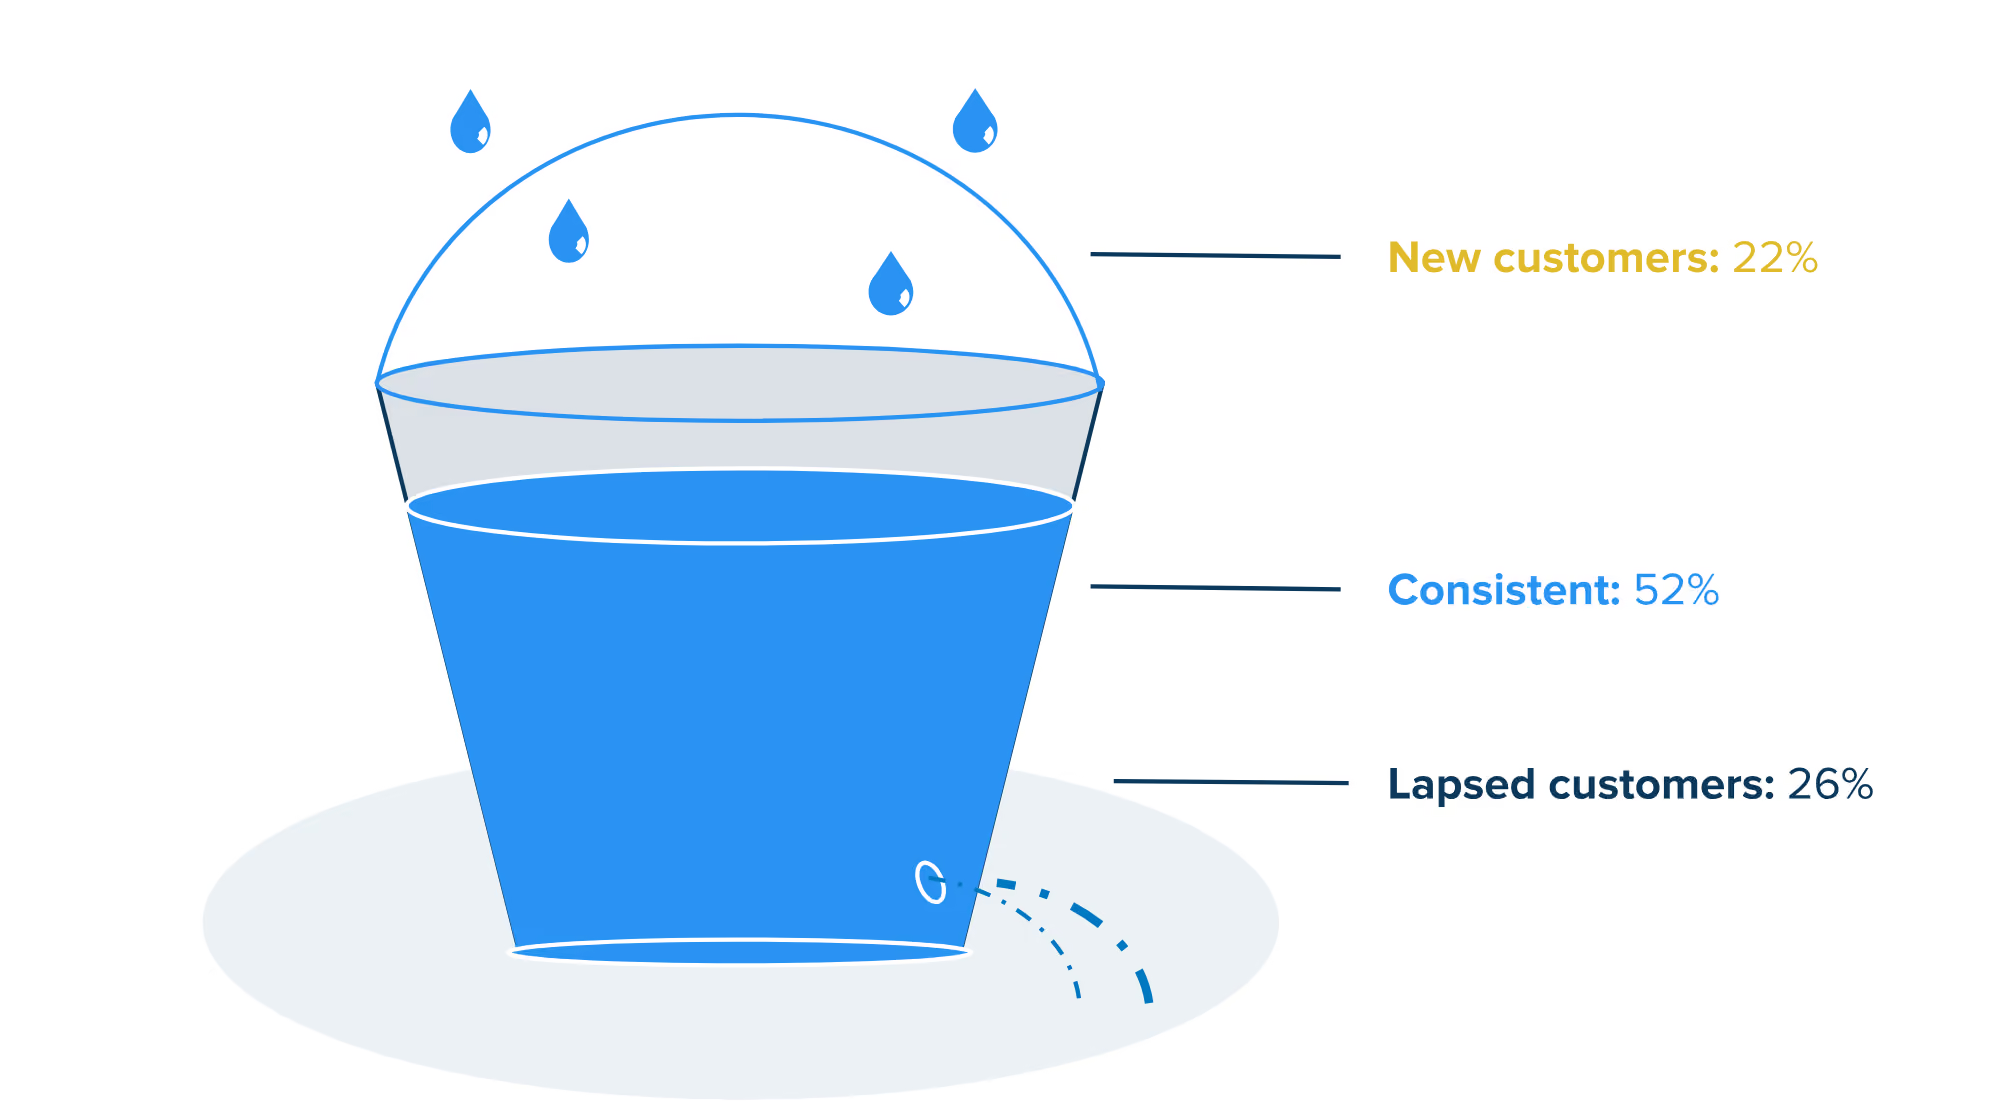
Overall, quarter over quarter, customers tend to stay in their same segment (36%) while there is an equal amount that increase/decrease loyalty (7%) and are either new or lapsed (22% and 26%, respectively). However, when digging into the individual segments, the opportunity becomes more clear among segments that are categorized as non-loyal.
Segment Movement
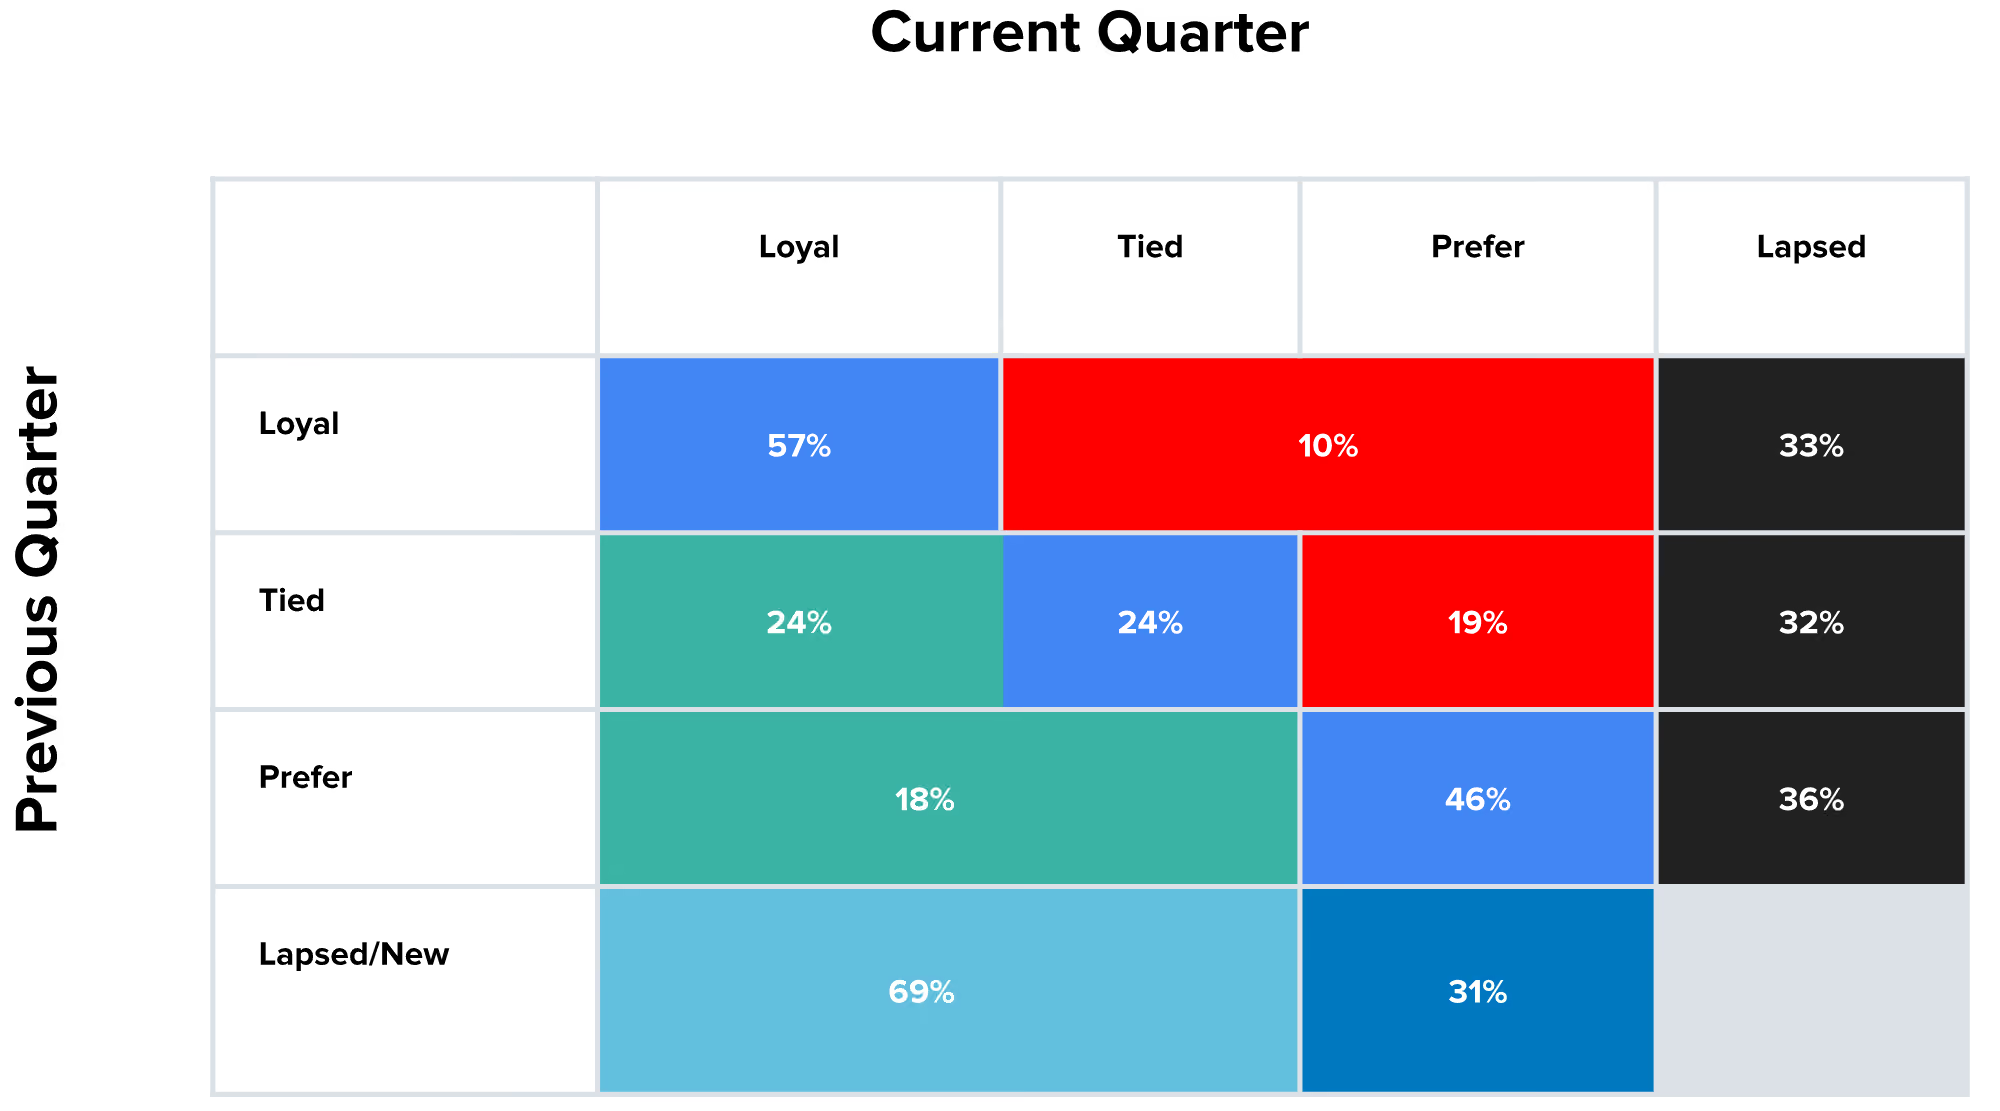
Of the ⅔ of each customer segment that is non-lapsed, those that are loyal to a specific airline tend to stay loyal (57%). However, those categorized as “non-loyal” (Tied/Prefer) show significant willingness to to shop around (43% and 46%, respectively).
Airline Leaky Bucket
Airlines are acquiring new customers yet even more existing customers are moving into the lapsed tier. This cycle is expected based on typical consumer behavior for airline travel quarter over quarter but reinforces need to nurture existing relationships .
Diving deeper into the individual segments tells us:
- Loyal customers typically do not switch airlines, which is most likely due to airlines robust loyalty programs and incentives. However, customers that are Tied or Prefer have a high propensity for behavior change and show an opportunity for targeted campaigns to influence their behavior.
- Lapsed customers are similar across all segments, which is reflective of typical airline purchasing behavior - regardless of their loyalty categorization.
Definitions of Customer Segments
Loyal Customers
Loyal: Only shop with a specific brand, or have the highest share of wallet with a given brand and relative rank is lower than all other brands in consideration set
Not Loyal Customers
Tied: Similar relative ranks to 2 or more brands regardless of share of wallet ranking
Prefer: Lower share of wallet and higher rank than other brands in their consideration set
Lapsed: Shopped historically but do not shop currently, as defined by the analysis time period
New: Shop currently but have not shopped historically, as defined by the analysis time period
Takeaways
Airline marketers’ inherent focus on nurturing loyal customers is well-know and consumer spend data show it’s working - Loyal customers tend to stay loyal. But huge opportunity exists with customers who are not loyal to any specific airline and could be lured through greater incentives. To stay top of mind, marketers must continuously nurture relationships, understand customer needs, and offer seamless experiences. To foster loyalty with your customers, consider these recommendations:
- Use an “always on” strategy to keep customers engaged, regardless of purchase frequency.
- Regularly update/refine customer segments and adjust reward offers to keep them engaged.
- Use targeted campaigns to boost loyalty and revenue.
Cardlytics can deliver a comprehensive Customer Loyalty Analysis with insights into customer behavior and movement across defined loyalty segments. Contact us for more details.
* For this report, we've selected the entire Airlines category in our data, collectively representing$58bn in annual card spend. This sample differs from the previous Customer Loyalty Analysis report.
About Cardlytics
Cardlytics (NASDAQ: CDLX) is a commerce media platform, powered by our publishers’ first-party purchase data, that makes commerce smarter and more rewarding for everyone. We offer a range of solutions to help advertisers and publishers, including financial institutions, grow and strengthen customer loyalty. With visibility into approximately half of all card-based transactions in the U.S. and a quarter in the U.K., Cardlytics enables advertisers to engage consumers at scale and drive incremental sales through our industry-leading financial media network. Publisher partners can enhance their platforms with relevant and personalized offers that improve the shopping experience for their customers. Cardlytics also offers identity resolution capabilities through Bridg, which helps convert anonymous shoppers into known and reachable customers. Headquartered in Atlanta, Cardlytics has offices in Menlo Park, Los Angeles, Champaign, New York and London. Learn more at www.cardlytics.com or follow us on LinkedIn.
UK Loyalty Movement Report: QSR
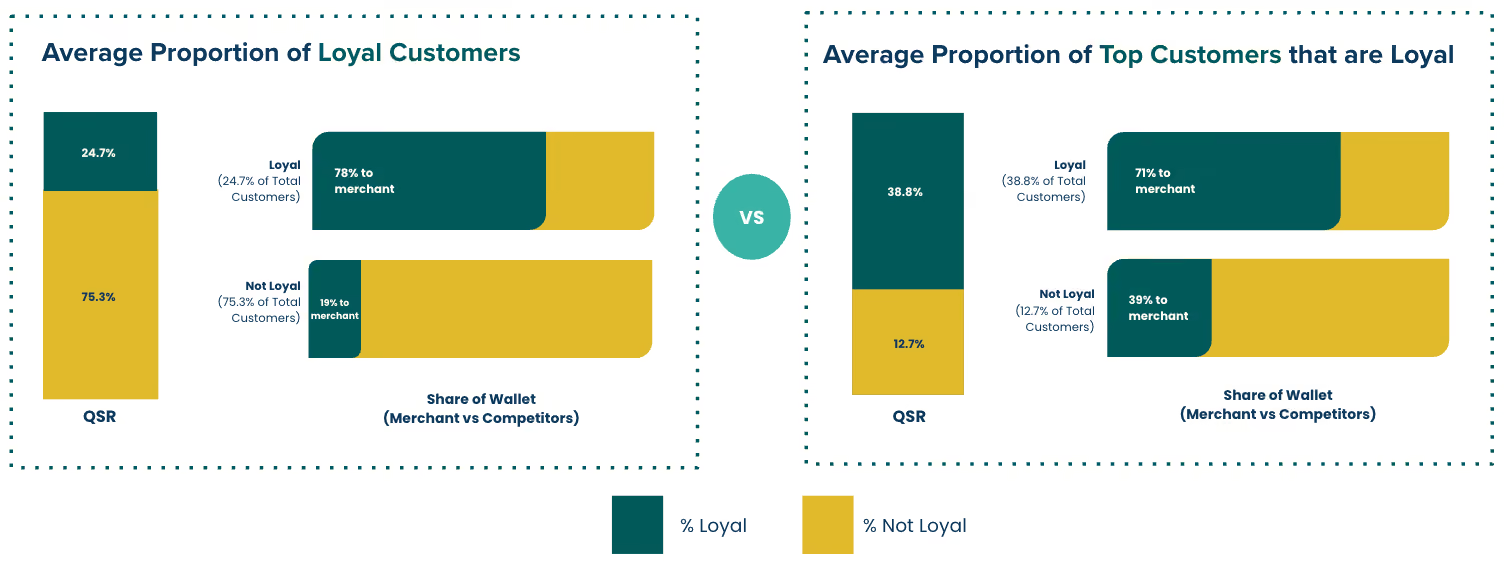
In this Report, we dive into customer behavior in the QSR category to better understand engagement over time by analyzing more than £5.8bn in consumer spend behavior
Introduction
In our previous report, Redefining Customer Loyalty, Cardlytics defined loyalty as a consumer’s preference for a merchant over its competitors. We analyzed billions in spending across six industries to measure customer loyalty and spending patterns with both loyal and non-loyal customers.
But customer behavior isn’t fixed—customers shift between loyalty segments over time. Understanding these shifts helps identify churn and informs strategies to nurture relationships and move customers to higher loyalty segments. In this Report, we dive into customer behavior in the QSR category to better understand engagement over time by analyzing more than £5.8bn in consumer spend behavior.*
Findings: loyalty is fluid, not fixed
We looked into purchase data at all QSRs in the UK over the last 8 quarters (Q1-23 through Q4-24) on a quarter by quarter basis to see whether even the “most loyal” customers showed changes in their purchase behavior.
QSR Loyalty Movement
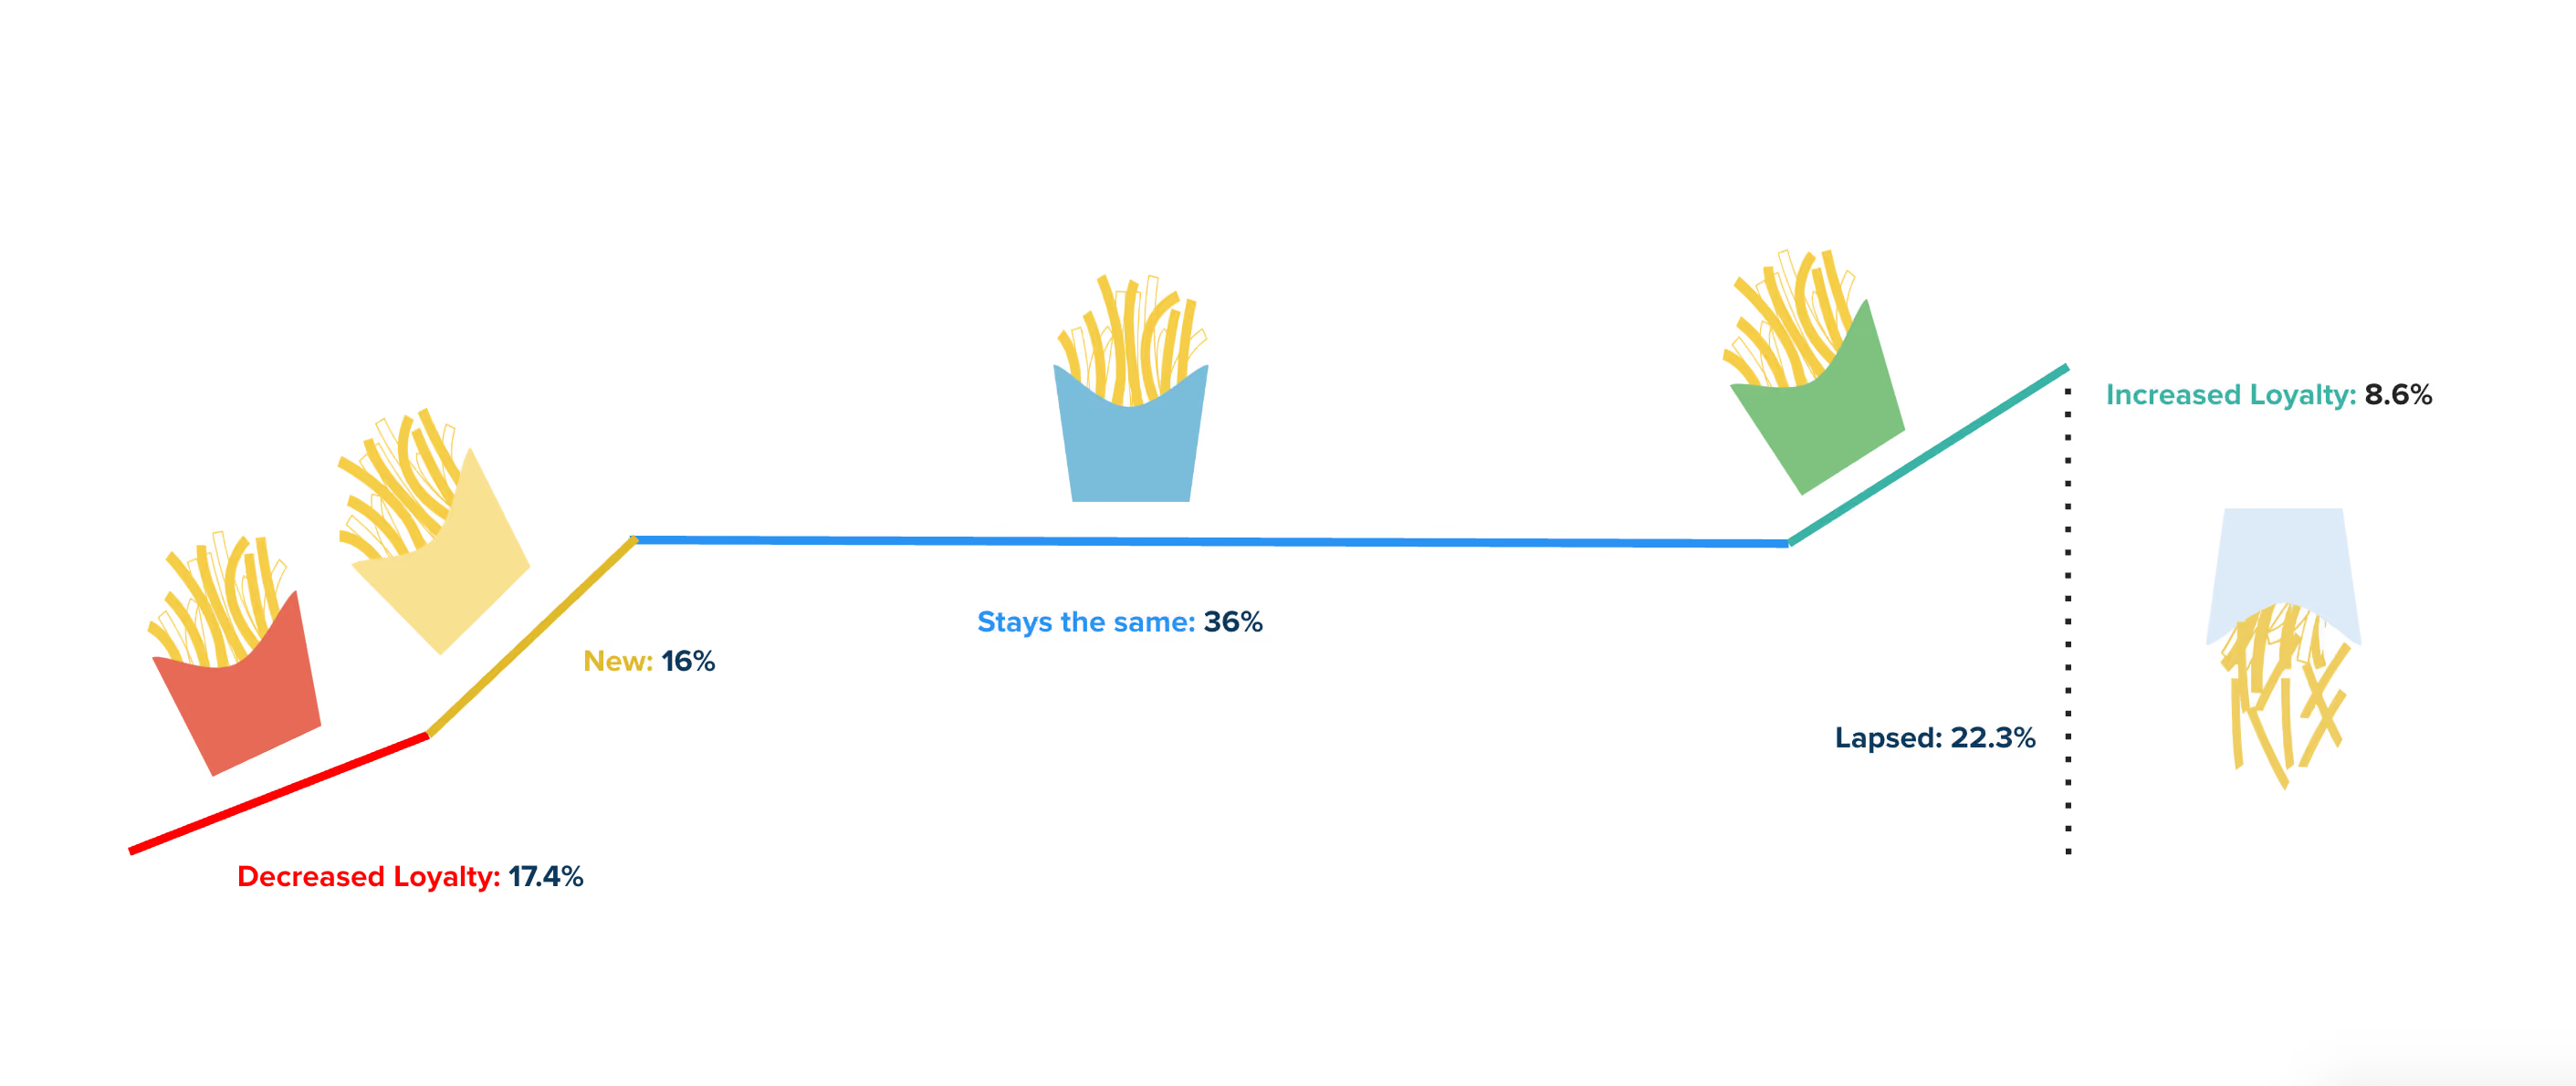
Overall, quarter over quarter, 36% of customers tend to remain in their existing segments and 26% increase or decrease their loyalty to a merchant, showing that QSR customers tend to be more promiscuous than other industries. Also, there is much more extensive customer loyalty movement within the “not loyal” segments.
Findings: segment movement
Diving deeper into the individual segments tells us:
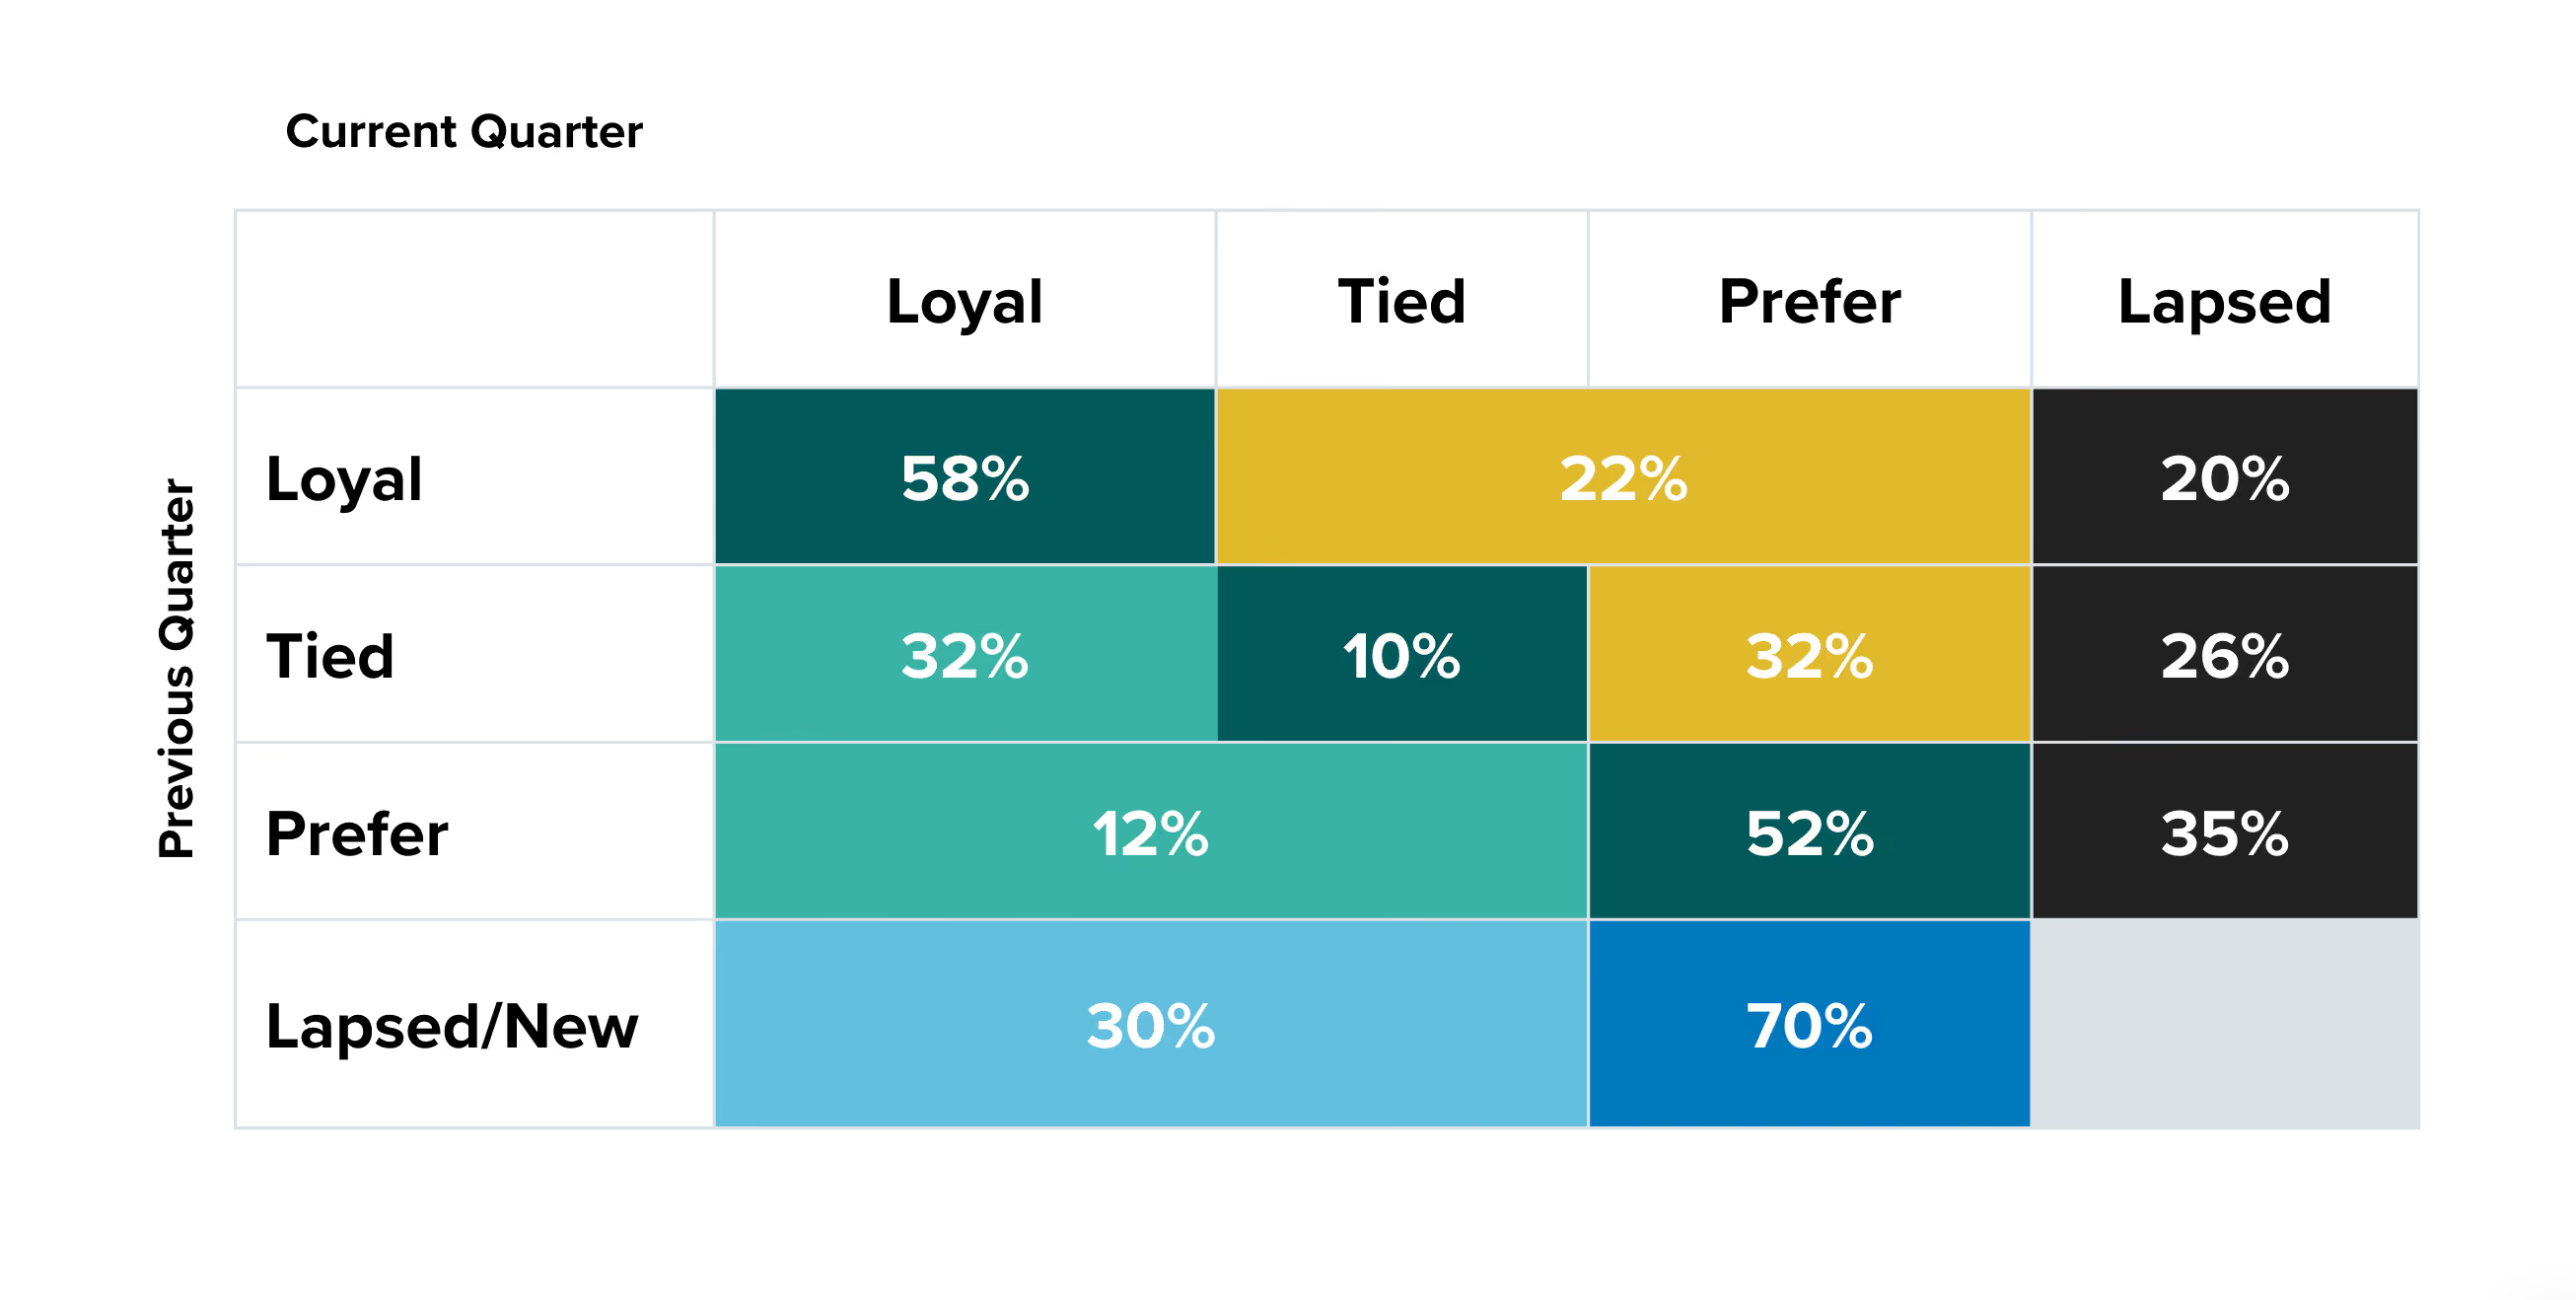
- Loyal customers are the most stable, with 58% staying Loyal.
- Prefer customers also show strong retention — 52% remain in that segment.
- Tied customers are the most fluid — only 10% stay Tied, while 58% shift into Loyal or Prefer.
- Churn risk is highest for Prefer customers, with 35% lapsing — nearly 2x higher than Loyal customers (20%).
Segment movement
Customer movement is happening across all segments, but the Tied group shows the highest churn – only 10% remain Tied, while a combined 58% shift into either Loyal (32%) or Prefer (26%). This volatility signals an opportunity to convert mid-loyalty shoppers with targeted interventions.
QSR Leaky Bucket
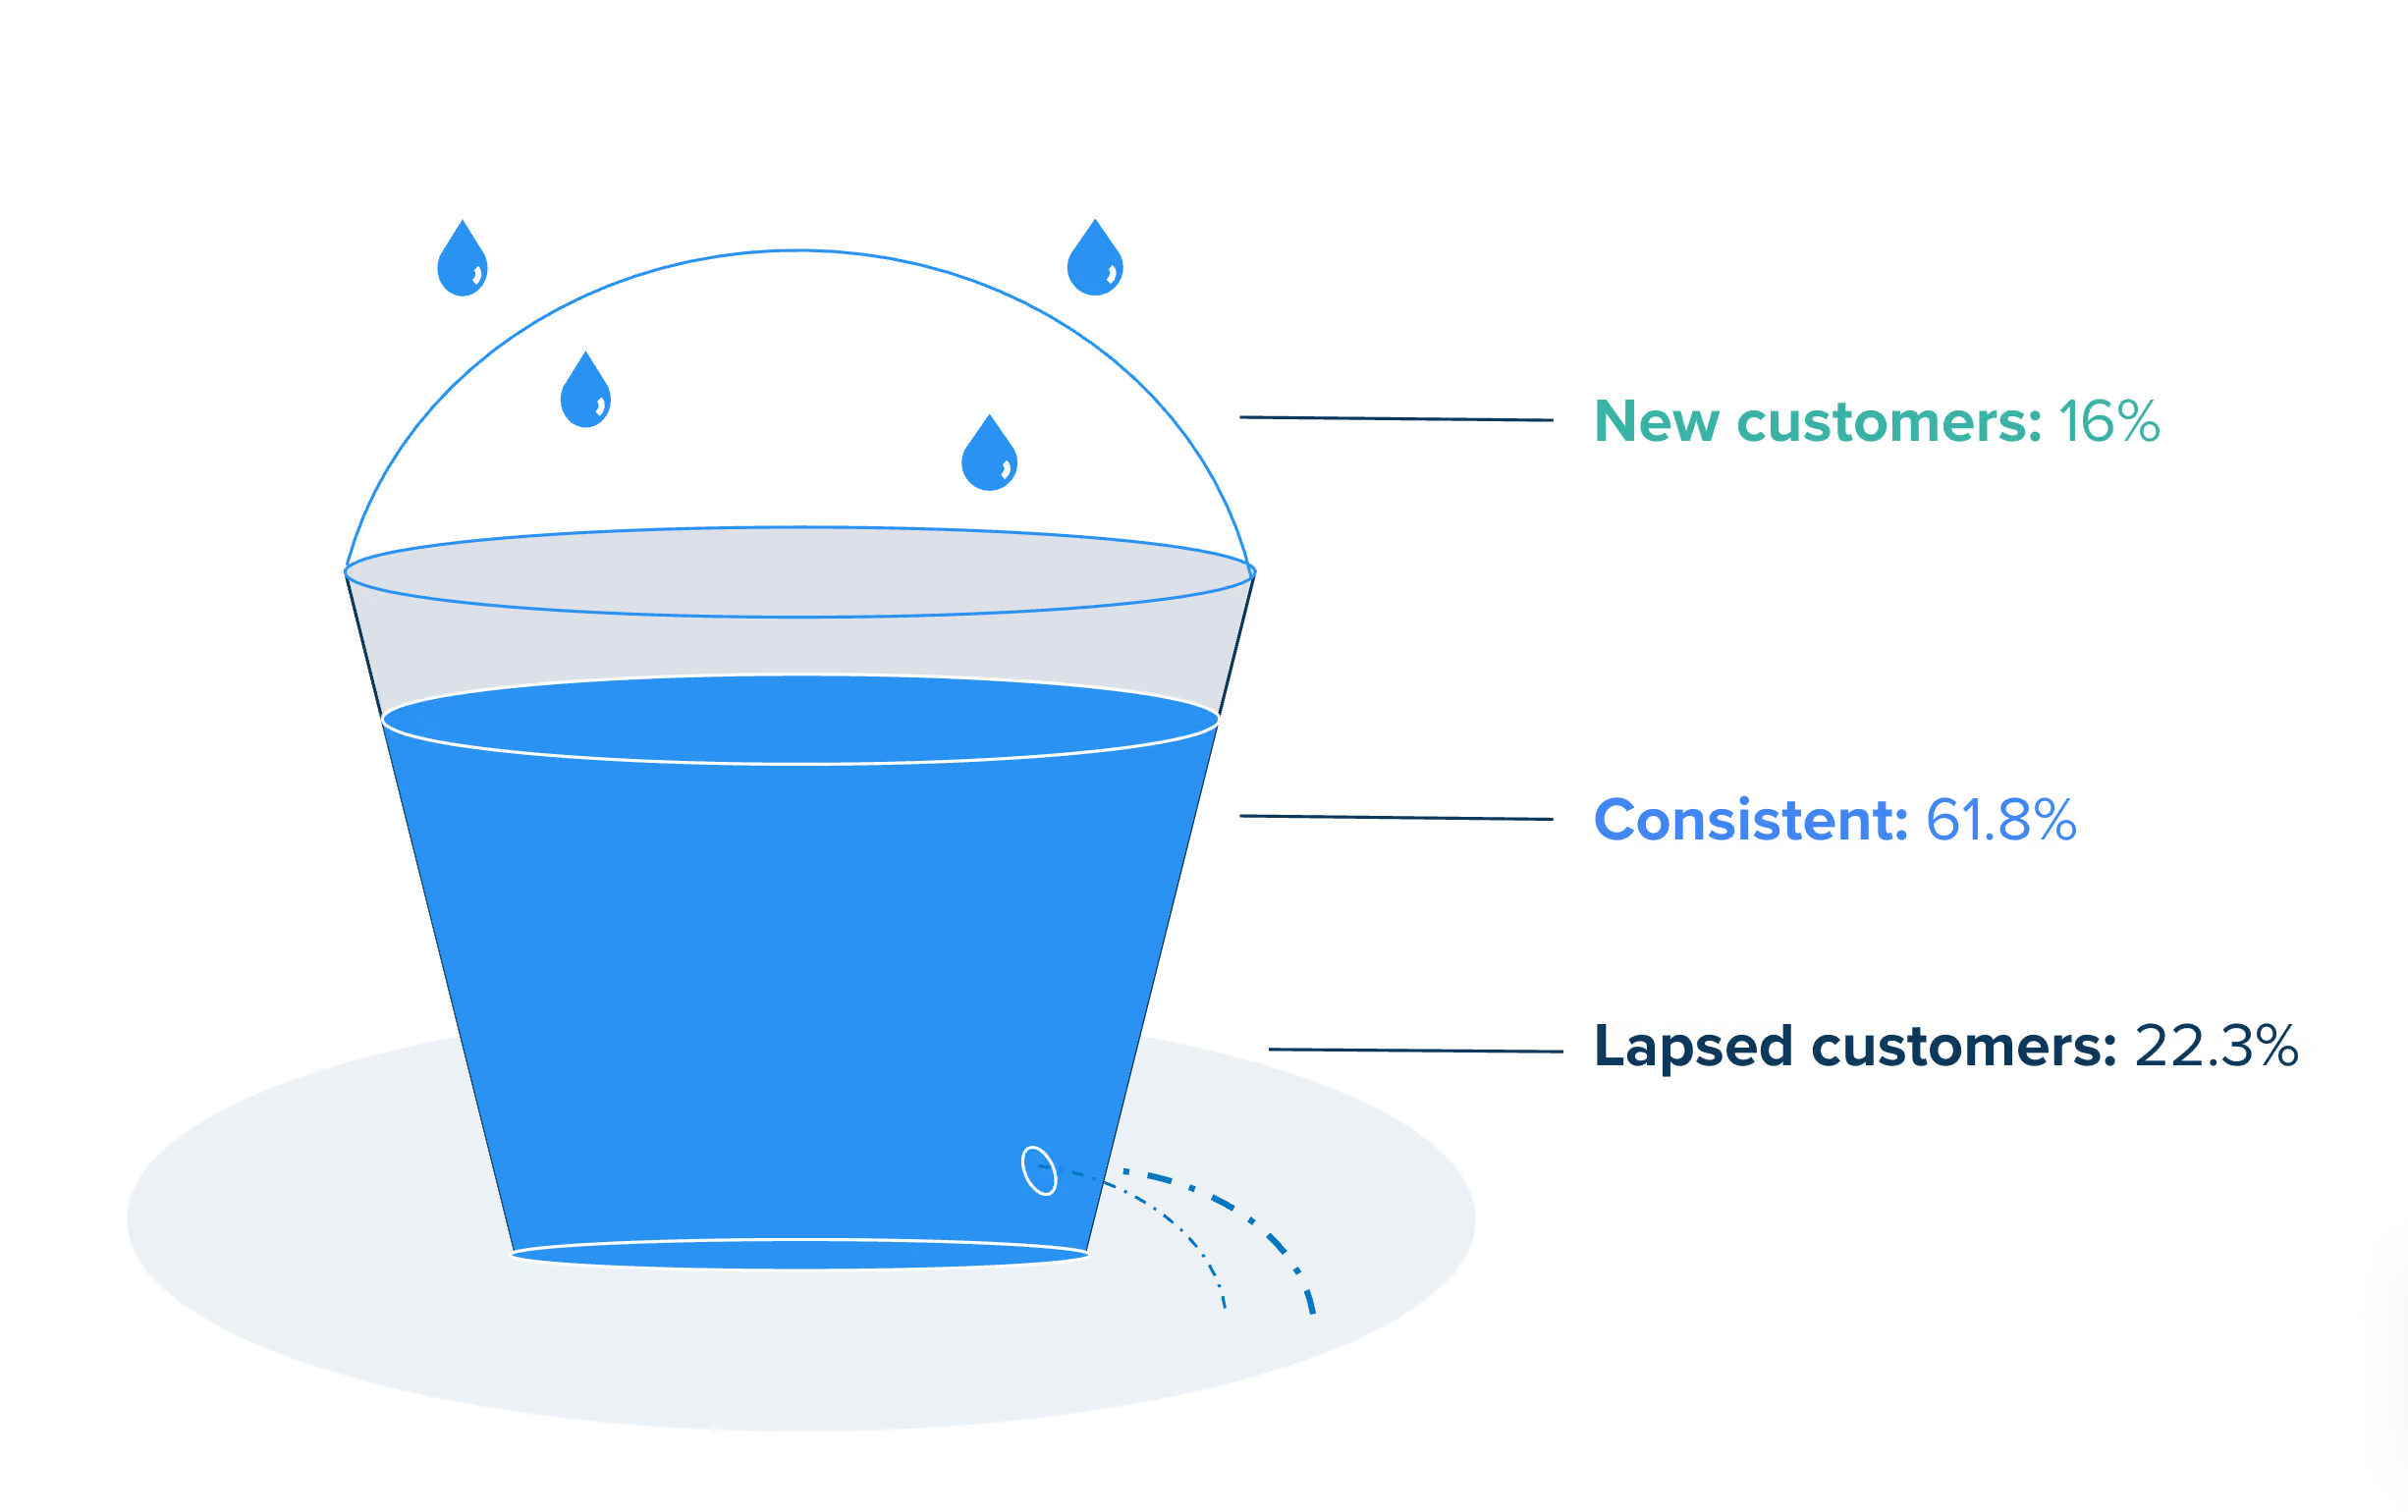
QSR brands are losing customers faster than they are acquiring them – with Lapsed customers (22.3%) outpacing New customers (15.9%). This signals a need to strengthen retention strategies to prevent long-term erosion of customer loyalty.
Takeaways: It’s more costly to acquire or re-acquire customers than to keep existing ones engaged.
Our analysis shows that 22% of QSR customers have lapsed, outpacing the 15.9% of new customers being acquired. Brands are at risk of net customer loss unless they prioritise loyalty-building efforts.
Our segment movement data also reveals that “Tied” customers are the most fluid, with 90% shifting into other behaviours — with both gains and losses. In contrast, Loyal customers remain relatively stable, and Prefer customers show moderate retention.
To protect and grow market share, marketers must go beyond acquisition. Nurturing relationships and strengthening loyalty can have a direct impact on retention and revenue.
To foster loyalty, consider these recommendations:
- Deploy an “always-on” strategy to stay connected with customers, regardless of purchase frequency.
- Continuously refine customer segments and tailor reward structures to reflect shifting behaviours.
- Launch targeted campaigns focused on converting fluid segments (like Tied and Prefer) into Loyal customers.
Loyalty Movement Report: QSR
In our Loyalty Movement Report, we dive into customer behavior in the QSR category to better understand engagement over time by analyzing more than $400B in consumer spend behavior.
The Secret Sauce to Retaining Customers
Introduction
In our previous report, Redefining Customer Loyalty, Cardlytics defined loyalty as a consumer’s preference for a merchant over its competitors. We analyzed $160B in spending across six industries to measure customer loyalty and spending patterns with both loyal and non-loyal customers.
But customer behavior isn’t fixed—customers shift between loyalty segments over time. Understanding these shifts helps identify churn and informs strategies to nurture relationships and move customers to higher loyalty segments. In our Loyalty Movement Report, we dive into customer behavior in the QSR category to better understand engagement over time by analyzing more than $44B in consumer spend behavior.*
QSR Category Loyal Customers
On average, 81% of the category’s customers are not actually loyal to any brand. But the loyal segment has a much higher share of wallet (67%) than a not loyal segment (15%).
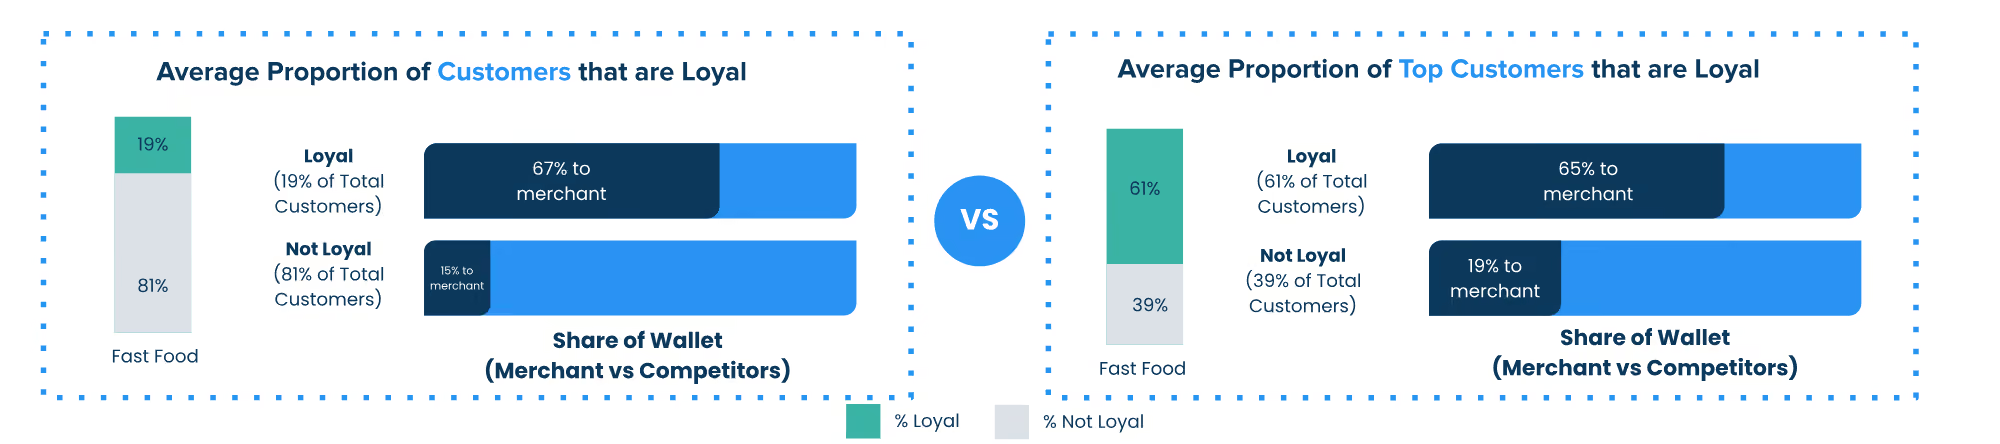
Top Customers (top 10% of most frequent transactors) are show reverse allegiance vs overall customers. And the loyal customer segment shows more than 3x higher share of wallet.
Findings
We looked into purchase data at all QSRs in the US over the last 8 quarters (Q1-23 through Q4-24) on a quarter by quarter basis to see whether even the “most loyal” customers showed changes in their purchase behavior.
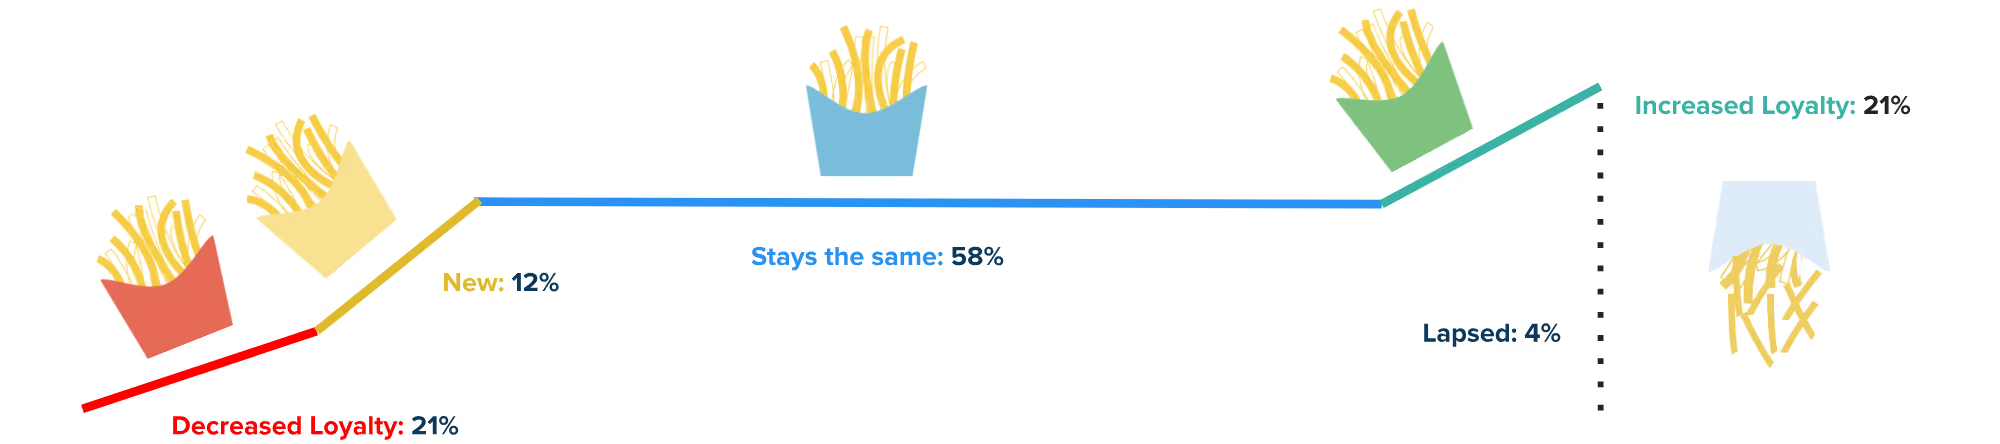
QSR Loyalty Movement
Overall, quarter over quarter, 58% of customers tend to remain in their existing segments and 21% increase or decrease their loyalty to a merchant, showing that QSR customers tend to be more promiscuous than other industries. Also, there is much more extensive customer loyalty movement within the “not loyal” segments.
Segment Movement
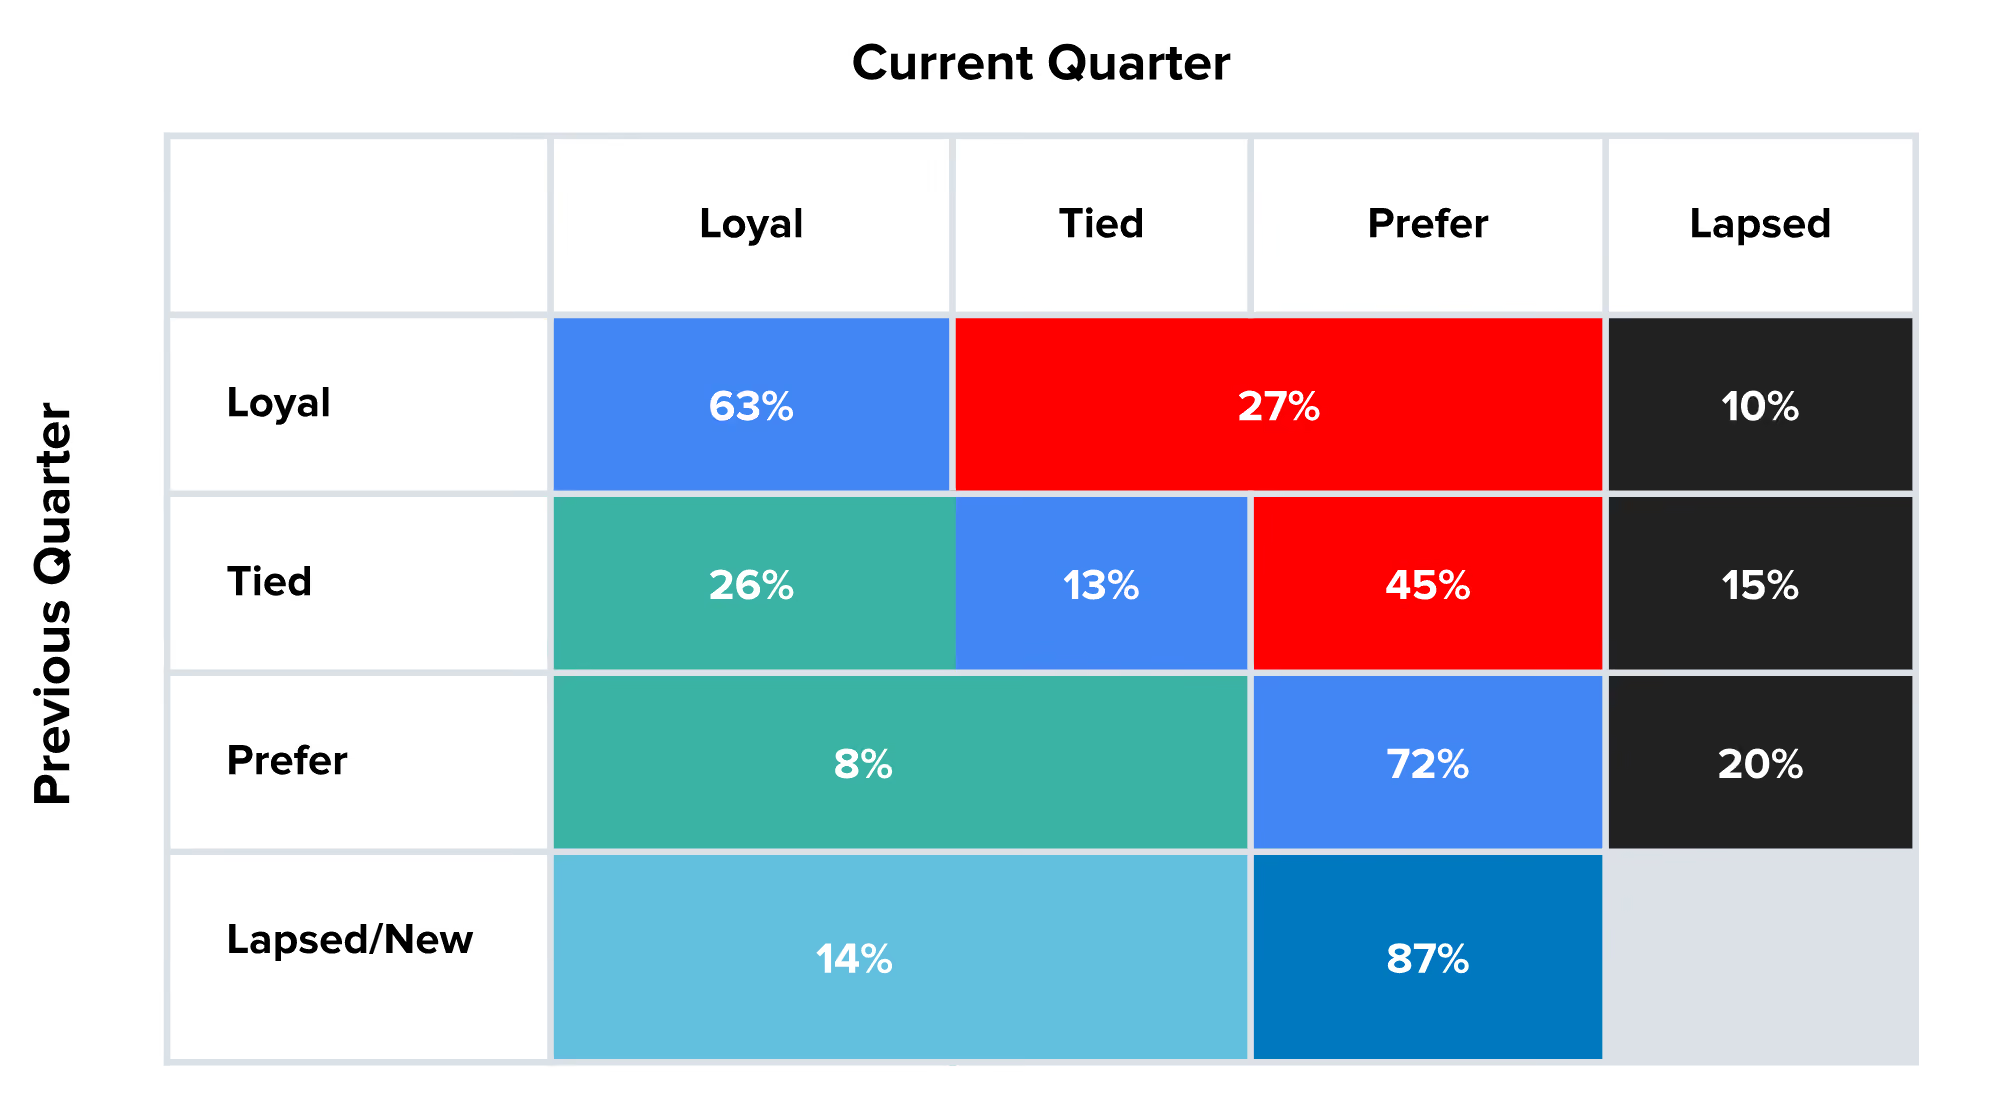
While all segments show purchase behavior movement, the Tied segment (part of Not Loyal customers) shows the most movement - both up (26%) and down (45%) - into other segments.
QSR Leaky Bucket
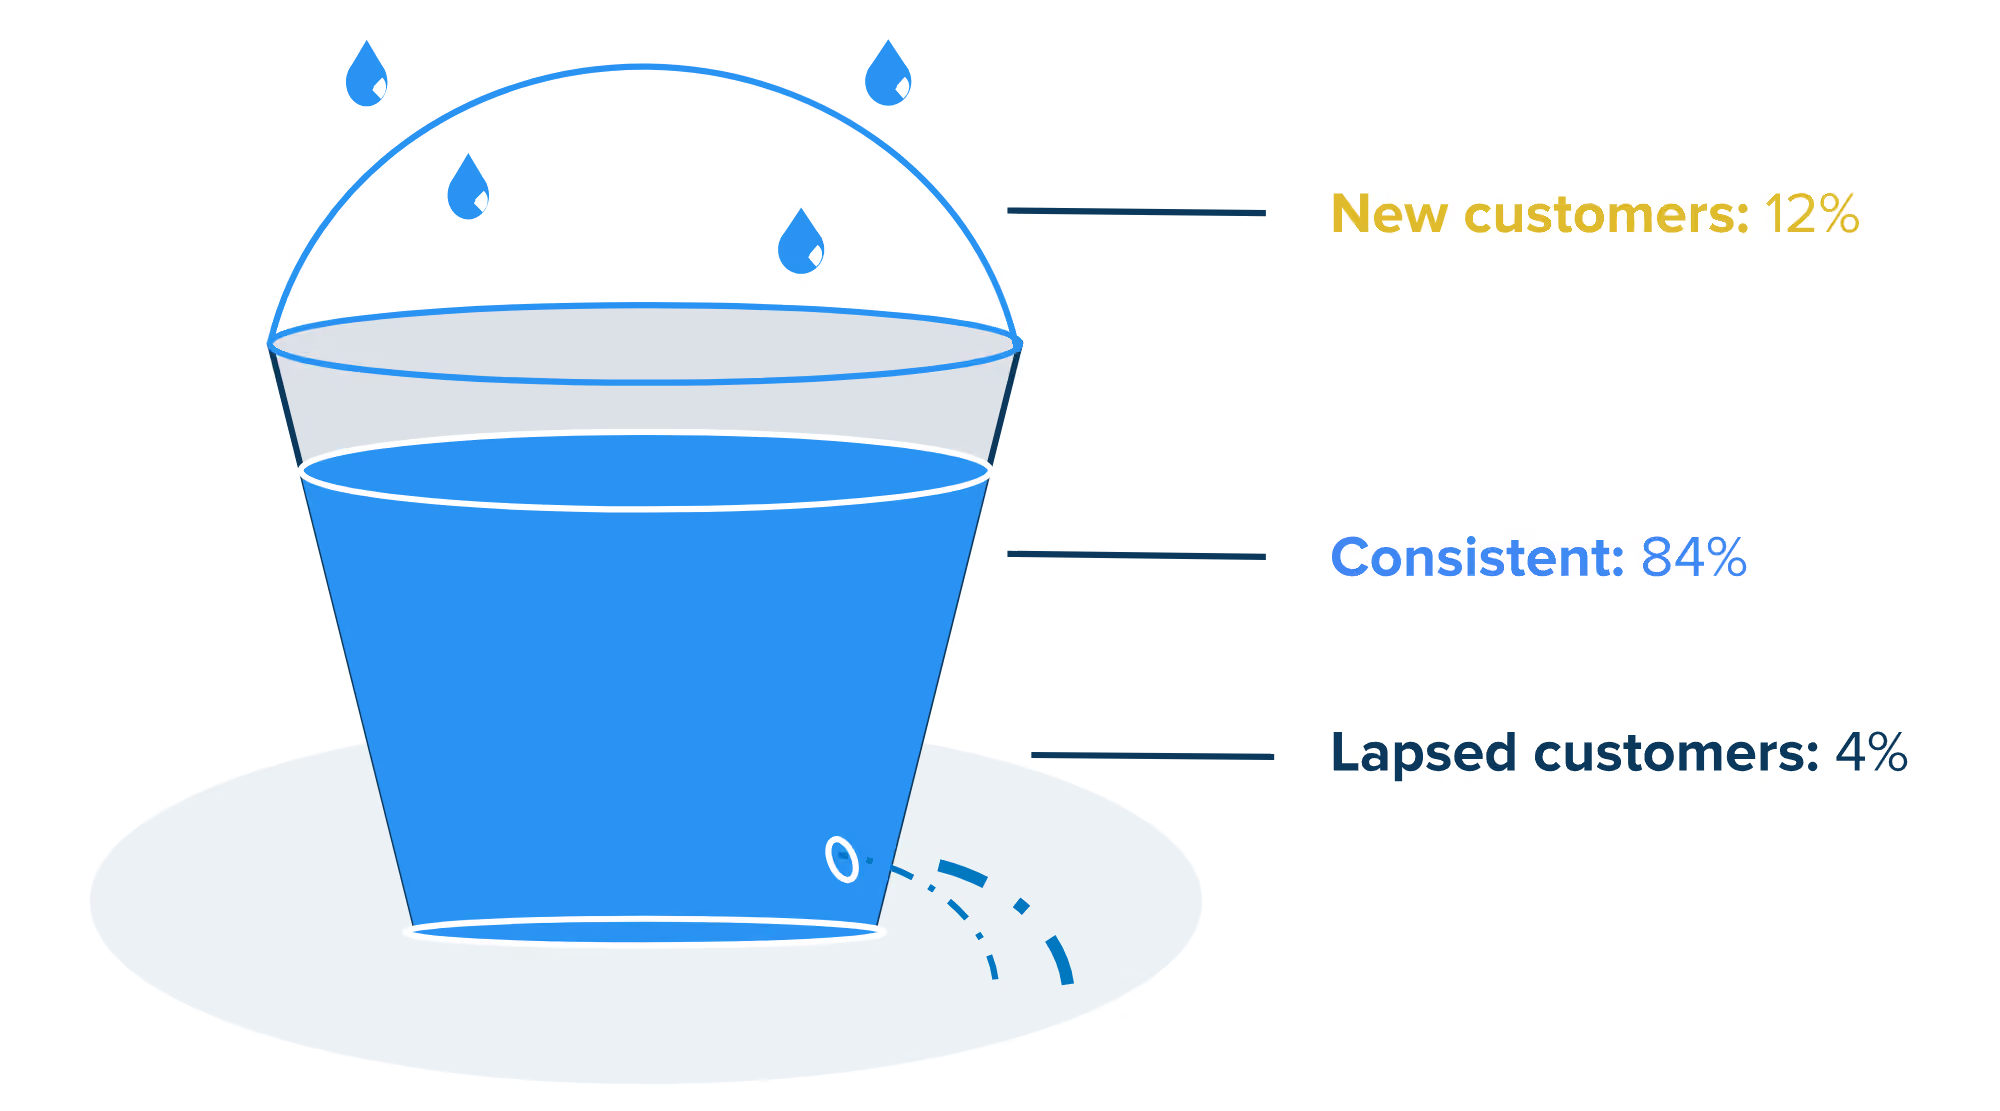
QSR brands are acquiring new customers at a 3x faster clip than they are losing customers. Yet these customers are less loyal to any specific brand so nurturing the relationship is key.
Diving deeper into the individual segments tells us:
- Loyal customers and those that Prefer the competition are the most rigid (with 63% and 72% staying the same, respectively). Those customers that are Tied have the greatest propensity for a behavior change (with only 13% staying the same).
- Loyal customers are far less likely to churn. Customers that are Tied are 50% more likely to churn and customers that Prefer the competition are 100% more likely to churn!
Definitions of Customer Segments
Loyal Customers
Loyal: Only shop with a specific brand, or have the highest share of wallet with a given brand and relative rank is lower than all other brands in consideration set
Not Loyal Customers
Tied: Similar relative ranks to 2 or more brands regardless of share of wallet ranking
Prefer: Lower share of wallet and higher rank than other brands in their consideration set
Lapsed: Shopped historically but do not shop currently, as defined by the analysis time period
New: Shop currently but have not shopped historically, as defined by the analysis time period
Takeaways
Marketers know it’s more costly to acquire or re-acquire customers than to keep existing ones engaged. When QSRs neglect current customers, they risk losing them and undoing past investment - not loyal customers are 50%-100% more likely to lapse/churn than loyal customers. But also QSRs are doing a relatively good job of bringing in new customers so staying top of mind is even more important. Marketers must continuously nurture relationships, understand customer needs, and offer seamless experiences. To foster loyalty with your customers, consider these recommendations:
- Use an “always on” strategy to keep customers engaged, regardless of purchase frequency.
- Regularly update/refine customer segments and adjust reward offers to keep them engaged.
- Use targeted campaigns to boost loyalty and revenue.
Cardlytics can deliver a comprehensive Customer Loyalty Analysis with insights into customer behavior and movement across defined loyalty segments. Contact us for more details.
* *For this report, we've selected the entire QSR category in our data, collectively representing over $44B in annual card spend. This sample differs from the previous Customer Loyalty Analysis report.
About Cardlytics
Cardlytics (NASDAQ: CDLX) is a commerce media platform, powered by our publishers’ first-party purchase data, that makes commerce smarter and more rewarding for everyone. We offer a range of solutions to help advertisers and publishers, including financial institutions, grow and strengthen customer loyalty. With visibility into approximately half of all card-based transactions in the U.S. and a quarter in the U.K., Cardlytics enables advertisers to engage consumers at scale and drive incremental sales through our industry-leading financial media network. Publisher partners can enhance their platforms with relevant and personalized offers that improve the shopping experience for their customers. Cardlytics also offers identity resolution capabilities through Bridg, which helps convert anonymous shoppers into known and reachable customers. Headquartered in Atlanta, Cardlytics has offices in Menlo Park, Los Angeles, Champaign, New York and London. Learn more at www.cardlytics.com or follow us on LinkedIn.
UK Loyalty Movement Report: Grocery
In this Loyalty Movement Report, we’ll dive deeper into customer in behavior in the UK across the Grocery category to better understand engagement over time.
Introduction
In our previous report, Redefining Customer Loyalty, Cardlytics defined loyalty as a consumer’s preference for a merchant over its competitors. We analysed billions in spending across six industries to measure customer loyalty and spending patterns with both loyal and non-loyal customers.
Customer behaviour isn’t fixed—shoppers move between loyalty segments over time. Our UK Grocery Loyalty Movement Report analyses national grocery spend to track these shifts, helping retailers identify churn, improve retention, and strengthen customer relationships.
Grocery Category Loyal Customers
On average, 75% of a merchant’s customers are not actually loyal. But the loyal segment (25%) has a much higher share of wallet (67%) than a not loyal segment (13%).
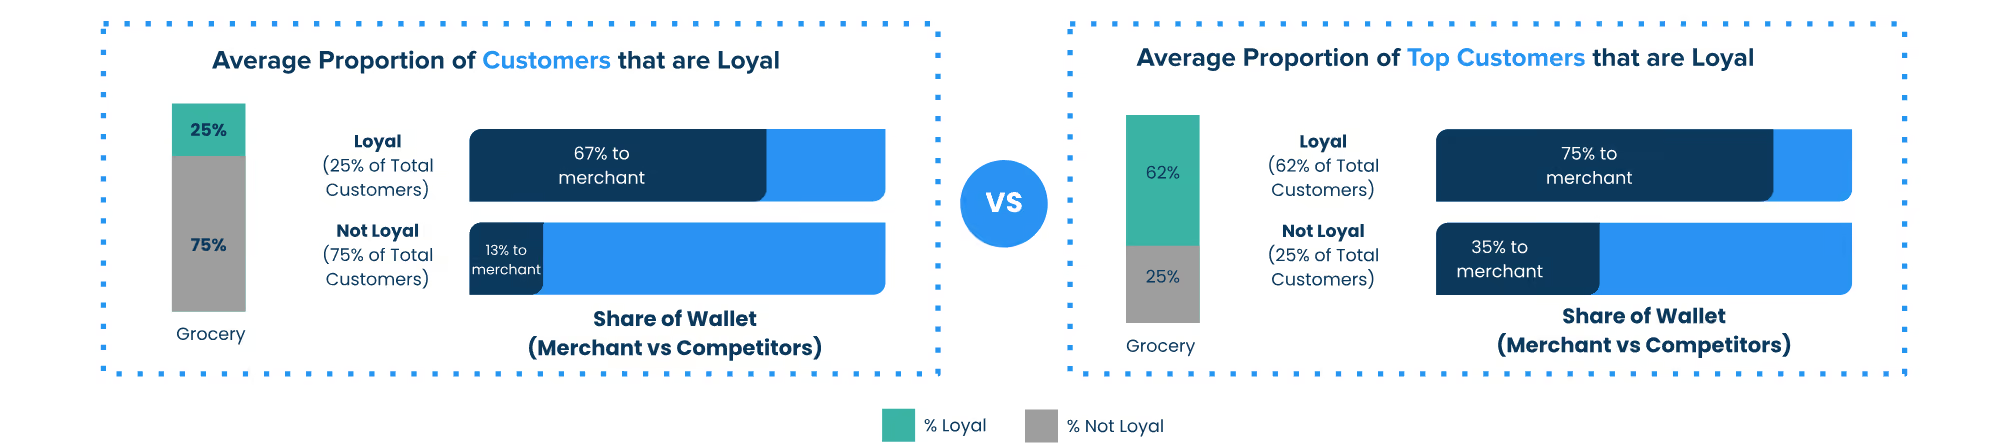
Top Customers (top 20% of most frequent transactors) still show that 25% are not loyal customers. Yet the loyal customer segment shows a 2x higher share of wallet.
Findings
We looked into purchase data at all groceries in the UK over the last 8 quarters (Q1-23 through Q4-24) on a quarter by quarter basis to see whether even the “most loyal” customers showed changes in their purchase behaviour.
Grocery Loyalty Movement
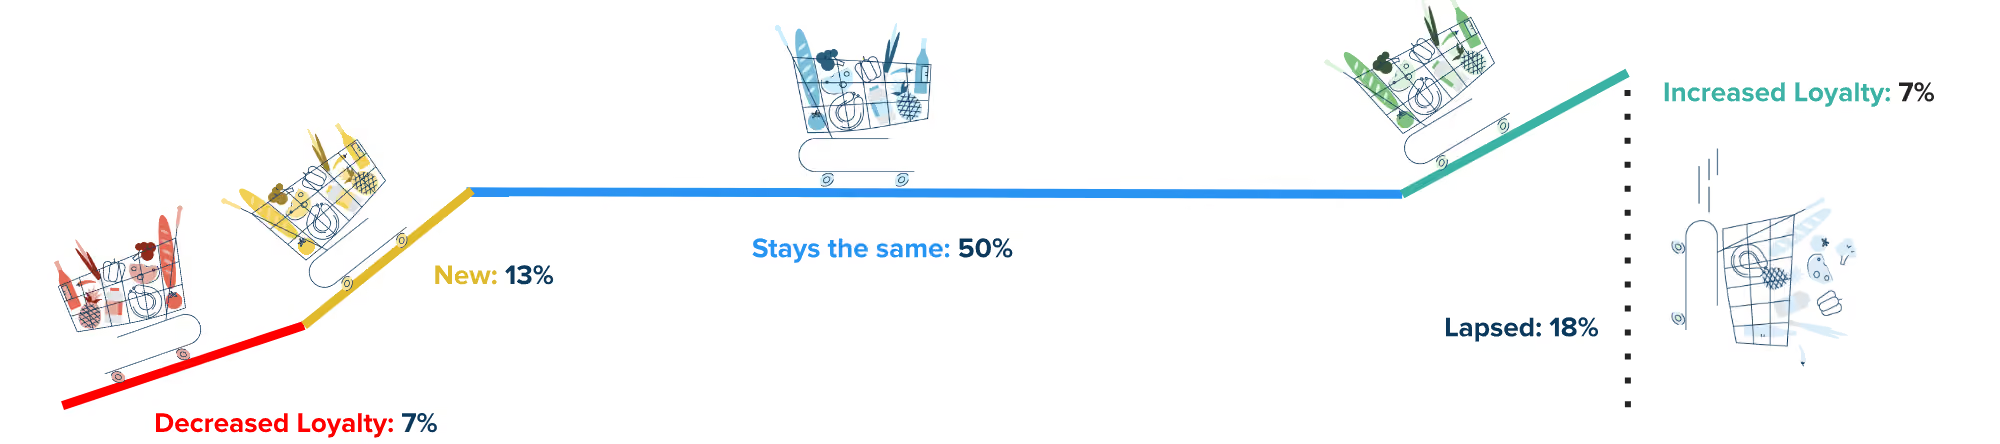
Overall, quarter over quarter, 50% of customers tend to remain in their existing segments while 50% increase or decrease their loyalty to a merchant. Yet there is much more extensive customer loyalty movement within the “not loyal” segments.
Segment Movement
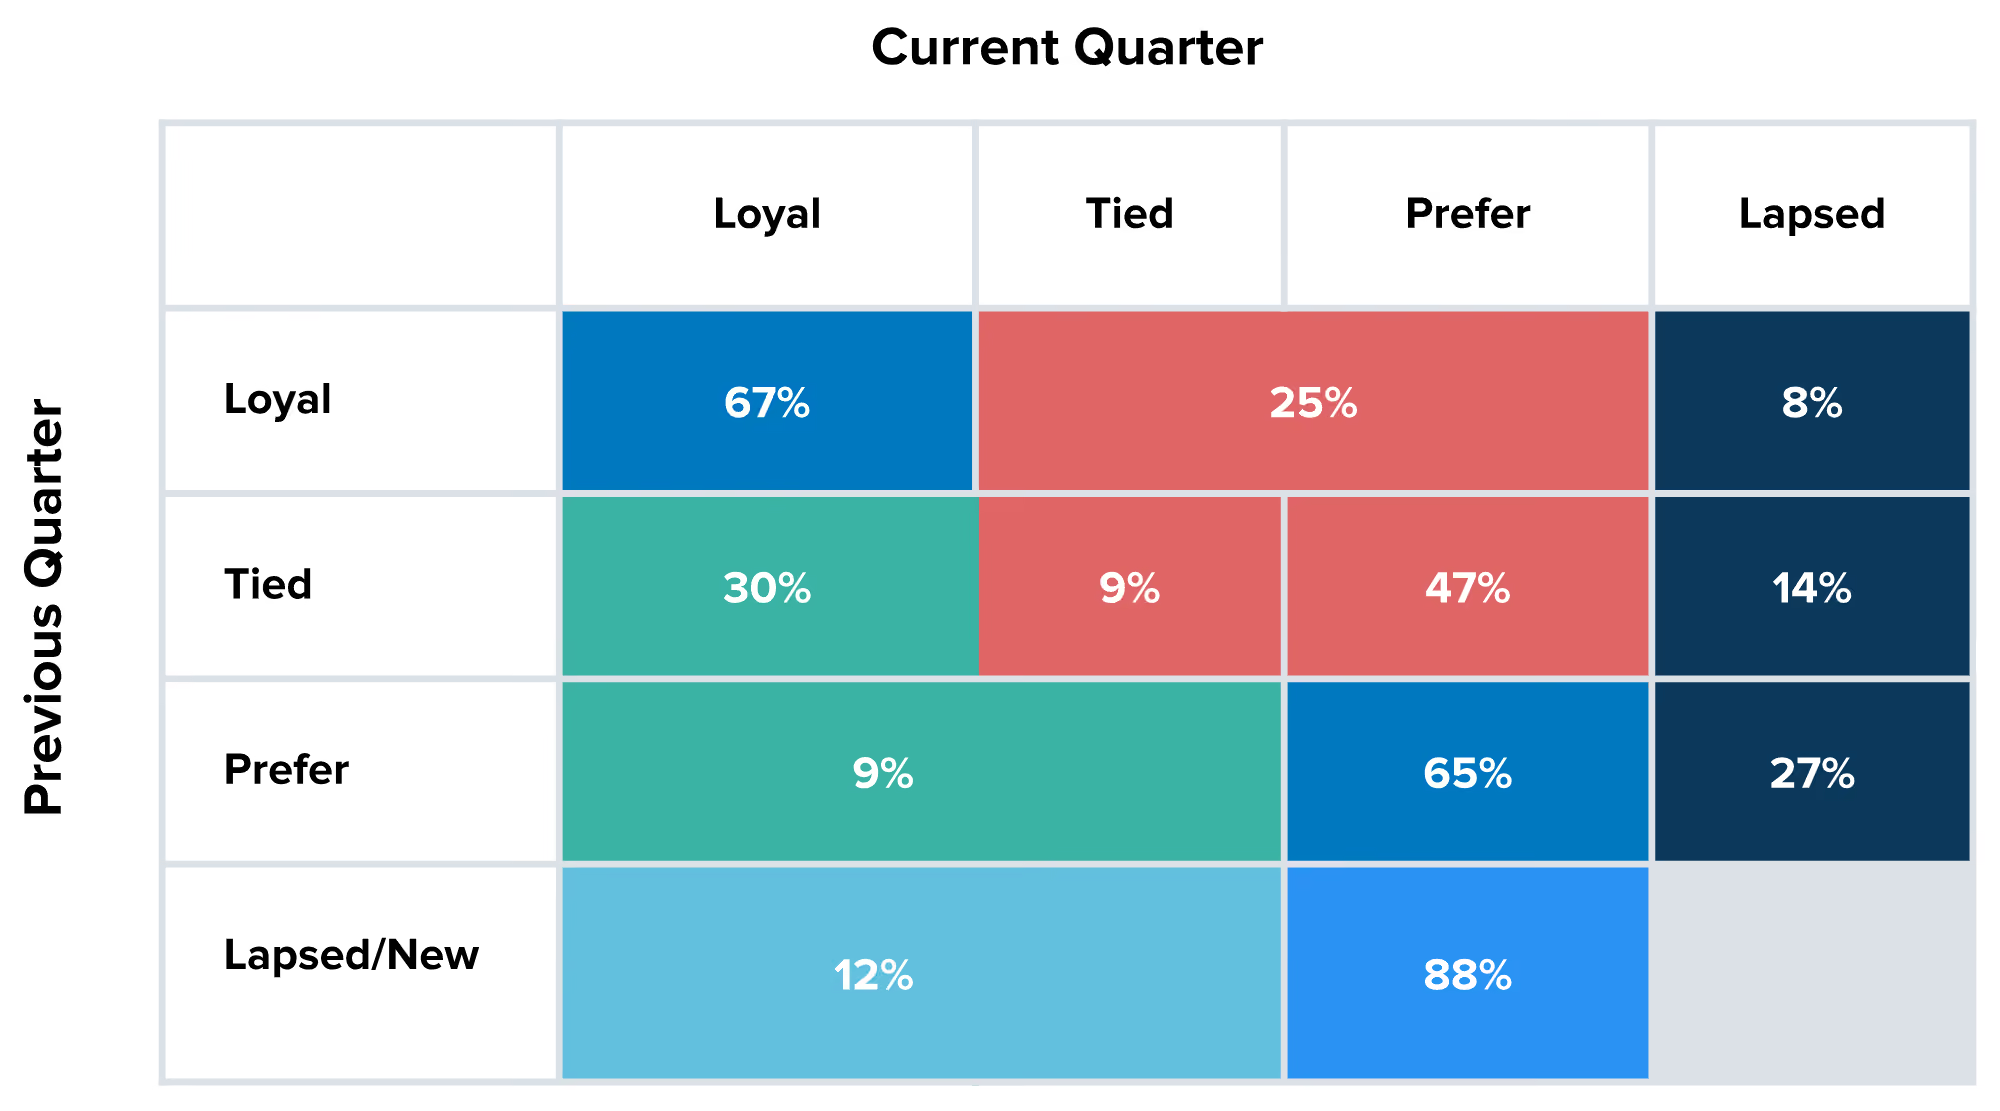
While all segments show purchase behaviour movement, the Tied segment (part of Not Loyal customers) shows the most movement - both up (30%) and down (47%) - into other segments.
Grocery Leaky Bucket
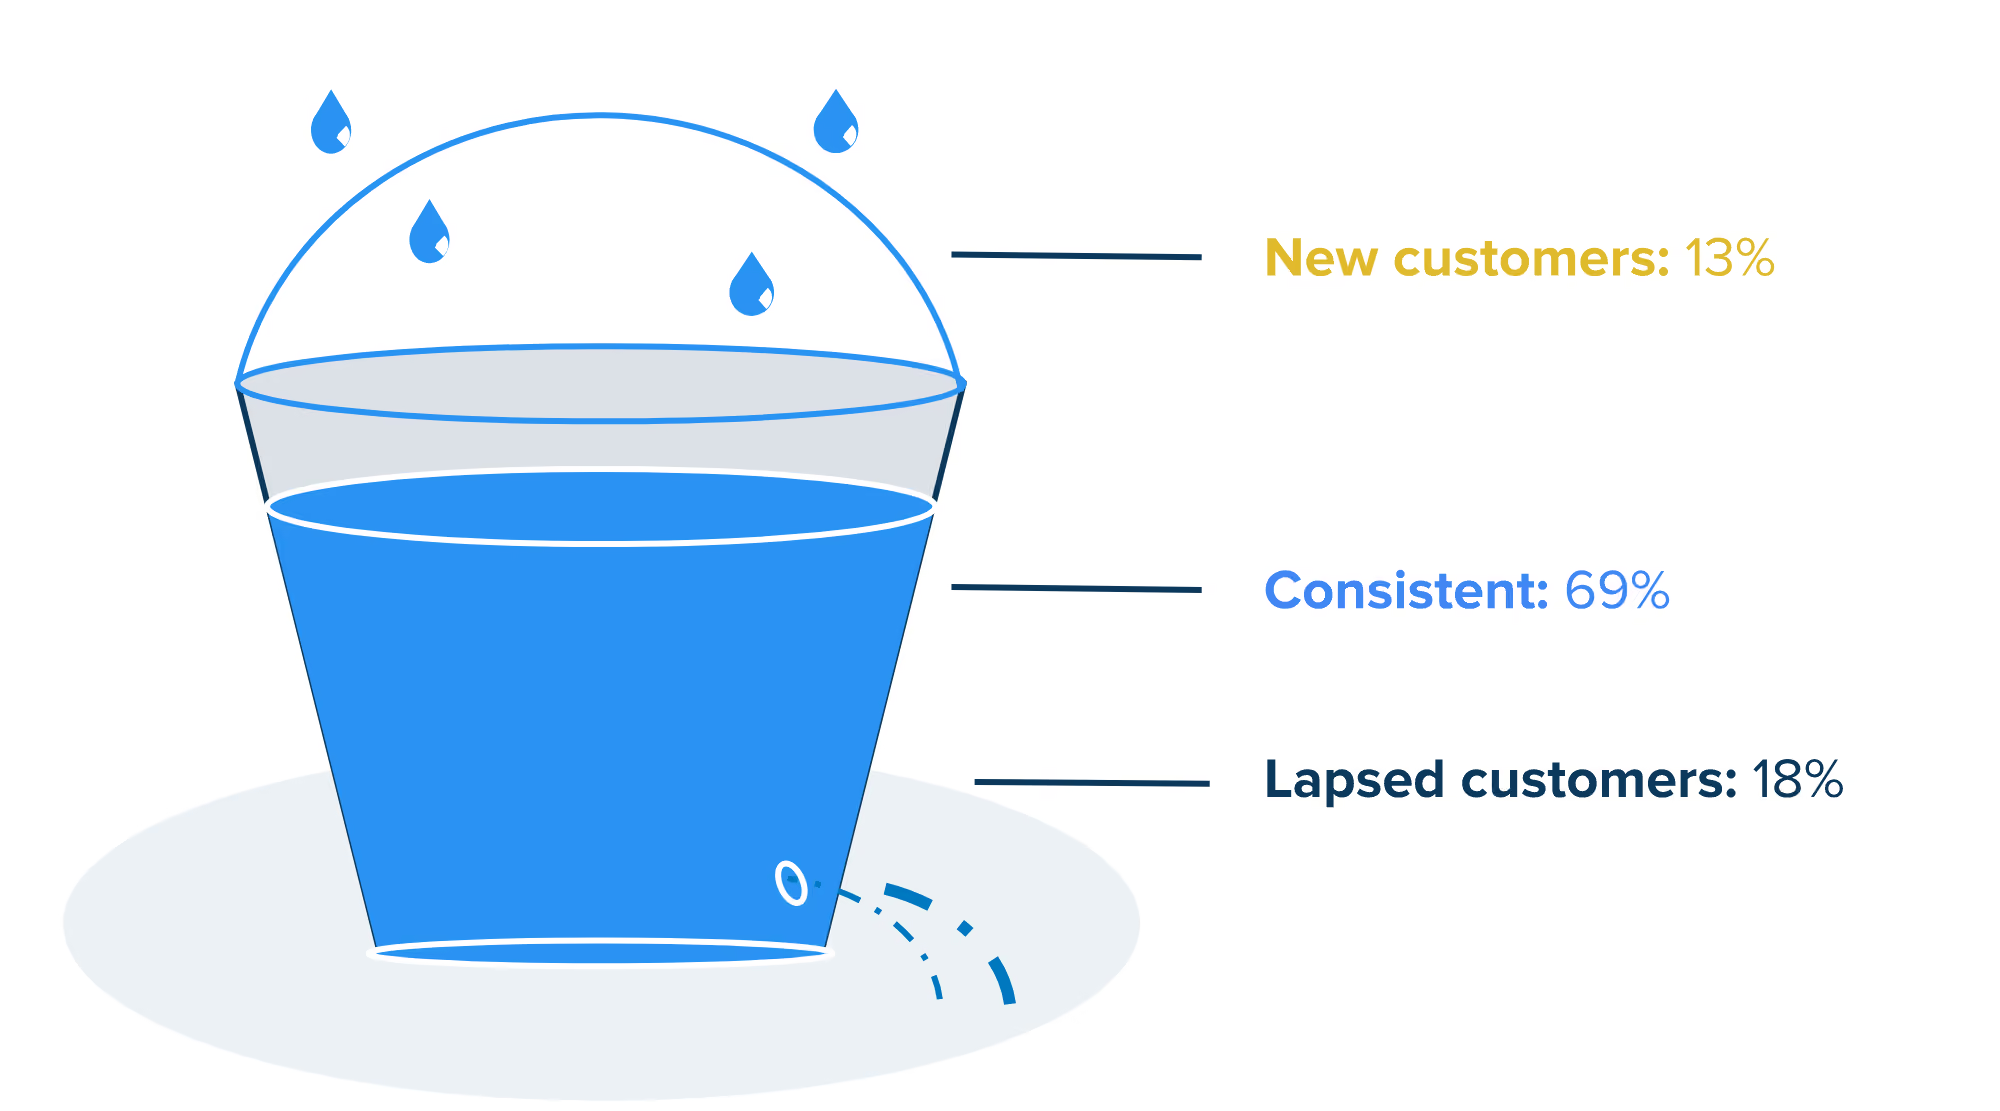
Grocery brands are acquiring new customers yet even more existing customers are moving into the lapsed tier. This cycle can be reversed by continuing to nurture existing customers.
Diving deeper into the individual segments tells us:
- Loyal customers and those that Prefer the competition are the most rigid (with 67% and 65% staying the same, respectively). Those customers that are Tied have the greatest propensity for a behaviour change, with only 9% staying the same, showing extreme volatility.
- Loyal customers are far less likely to churn. Tied Customers are 56% more likely to churn (moving to Prefer or Lapsed) and customers that Prefer the competition are 200% more likely to churn!
Definitions of Customer Segments
Loyal Customers
Loyal: Only shop with a specific brand, or have the highest share of wallet with a given brand and relative rank is lower than all other brands in consideration set
Not Loyal Customers
Tied: Similar relative ranks to 2 or more brands regardless of share of wallet ranking
Prefer: Lower share of wallet and higher rank than other brands in their consideration set
Lapsed: Shopped historically but do not shop currently, as defined by the analysis time period
New: Shop currently but have not shopped historically, as defined by the analysis time period
Takeaways - Building Grocery Loyalty in the UK
Loyalty in the UK grocery sector is highly unstable. Only 25% of shoppers are truly loyal, yet they contribute 67% of their share of wallet (SOW) to a single merchant. Even within the top customers, 25% are still not totally loyal. Loyalty is fragile and demands ongoing effort as competition is always close by. To stay top of mind, marketers must continuously nurture relationships, understand customer needs, and offer seamless experiences. To foster loyalty with your customers, consider these recommendations:
- Implement an always-on engagement strategy to keep customers connected, regardless of purchase frequency.
- Regularly update/refine customer segments and adjust reward offers to keep them engaged.
- Use targeted campaigns to boost loyalty and revenue.
Cardlytics provides comprehensive Customer Loyalty Analysis, delivering insights into loyalty movement, churn risk, and retention strategies to help grocery brands drive long-term customer value. Contact us to learn more
* For this report, we've selected the entire Grocery category in our data, collectively representing over $200bn in annual card spend. This sample differs from the previous Customer Loyalty Analysis report.
Get our insights delivered to you
Stay up to date. Subscribe now.